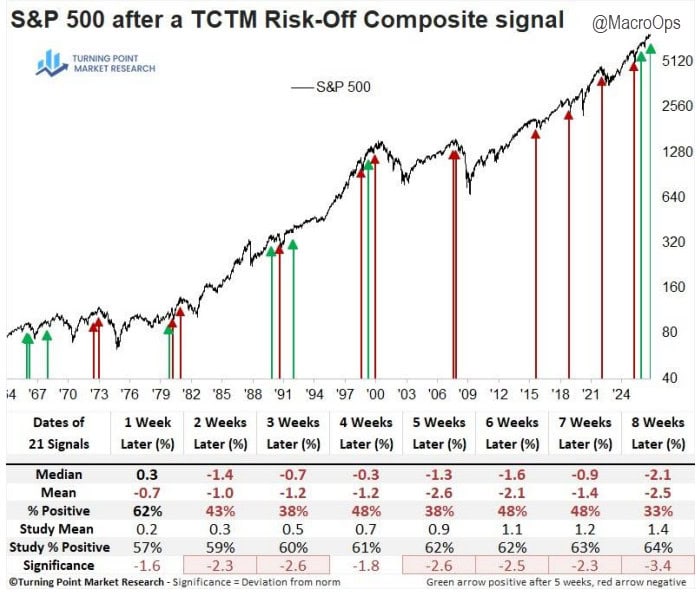
Summary: The rotation we called for started in earnest last week. The question now is whether this top-heavy market can do more than chop and vol sideways without the AI trade firing. Our TCTM Risk-Off signal suggests caution is warranted. AI capex and funding concerns are back in focus, right into the heart of earnings season. Positioning is quite low, and breadth is improving. The next move depends on earnings confirmation more than anything else: 14% of SPX reports hit this week, 44% the week after. This remains a do-little market with few great setups.
*** Housekeeping note: As some of you know, the MO team recently joined an established asset management firm to manage capital utilizing the MacroOps investment process — if you are a qualified purchaser (please see attached description) and are interested in learning more, please let us know.
We’ve also recently expanded the team — bringing Dean Christians on board — and are in the process of merging our companies.
In November, MacroOps will relaunch with a new brand, website, and interactive quantitative dashboard featuring our models and proprietary historical datasets.
With these changes, we’ll be more than doubling Collective pricing at the relaunch to preserve the size and quality of our community. If you’ve been on the fence, now is a good time to try it and see if it’s a fit.***
MO Portfolio & Trades
1. The portfolio rose +93bps last week and sits at +43.18% on the year, below our YTD high-water mark of +61%. We’re long Brent and heating oil futures, the BCOM Index, a few miners and energy plays, and select biotech and healthcare plays. We’re short silver, soybeans, and a small position in EUROSTOXX50.
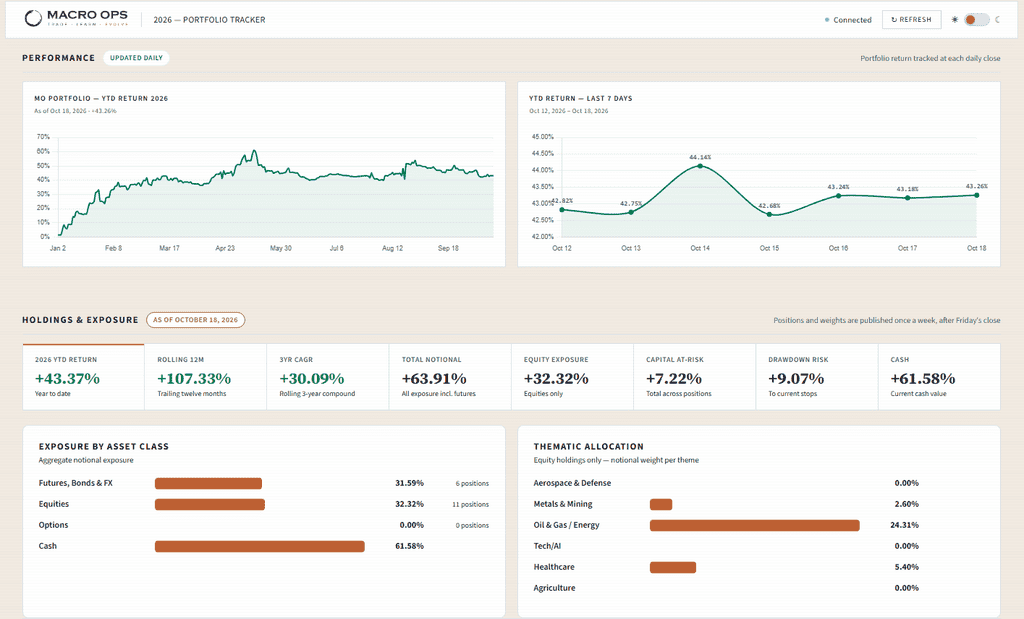
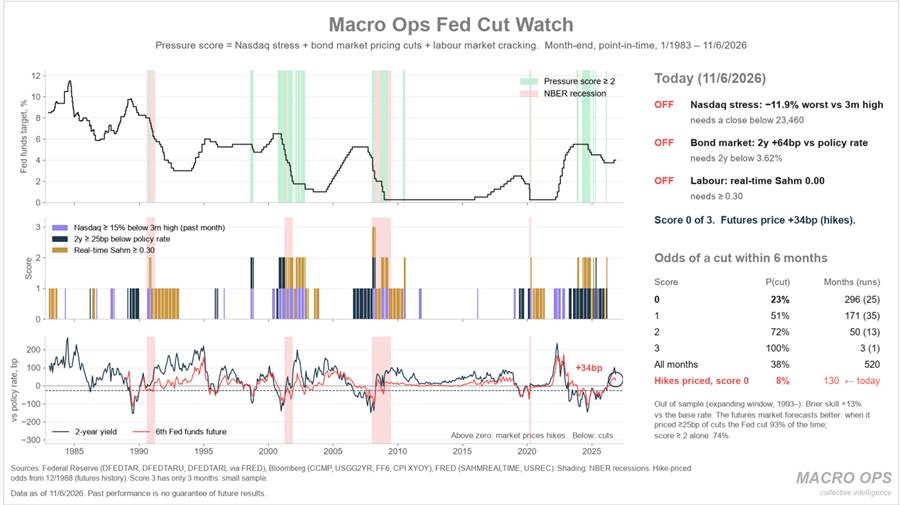
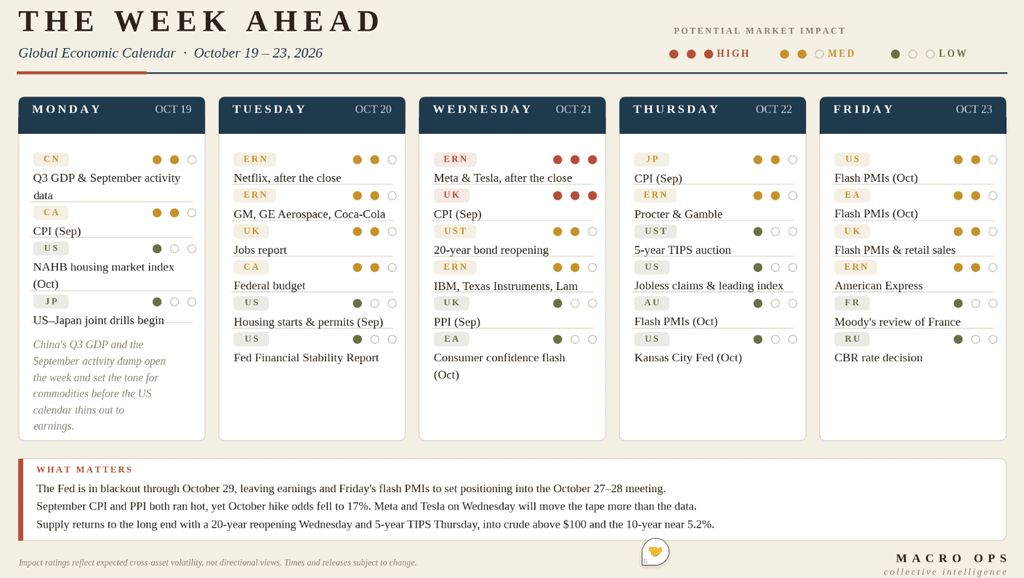
2. The week ahead in data. The Fed enters its blackout period through Oct 29th. September CPI and PPI both ran hot, yet October hike odds fell to 17%. Wednesday we have earnings from both META and TSLA. Meanwhile, Treasury supply returns Wednesday with a 20-year reopening and Thursday with five-year TIPS, as crude stays above $100 and the 10-year nears 5.2%.
3. From Mike G’s latest (link here): “For two weeks, we’ve flagged the tension between equities and energy. Both looked poised to rise. One had to give. Last week gave us the answer. The Nasdaq sold off sharply after stalling roughly halfway to the 1x measured-move target of its 3.5-month head-and-shoulders continuation. The small flag that formed at the end of September gave us a key level to raise stops, and we closed our Nasdaq long in the Macro Ops portfolio when the bull flag failed to follow through.”

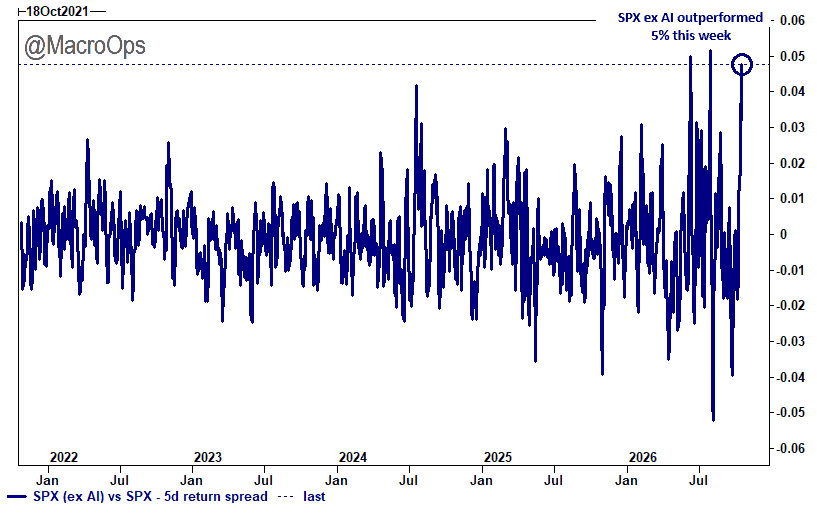
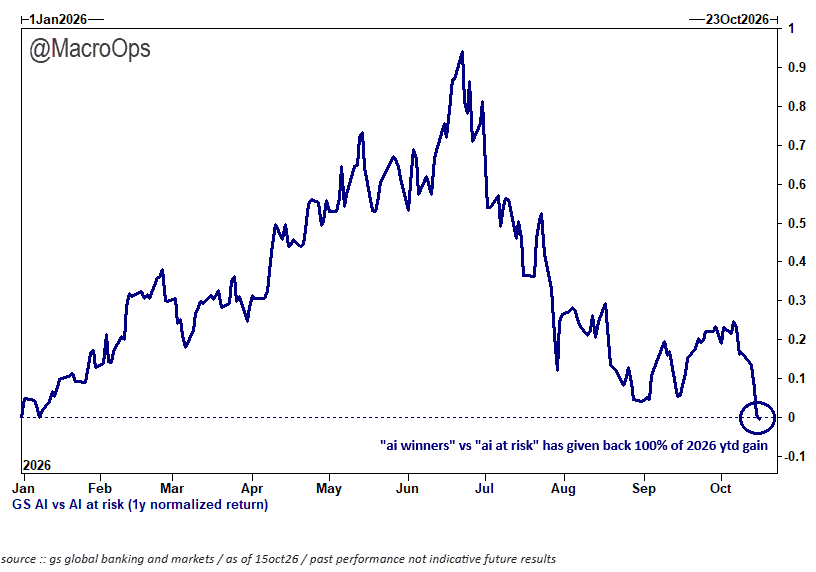
4. Last week I said rotation looked to be on the cards. That’s exactly what we got, with SPX ex AI outperforming by 5% (chart via GS).
5. This is a pretty incredible chart from GS. The “AI Winners” vs. “AI at Risk” trade has round-tripped 100% of its YTD gains. This explains the tough givebacks at many large funds this year; for example, Lone Pine and Brevan Howard have both given up nearly all of their 40%+ ytd gains.
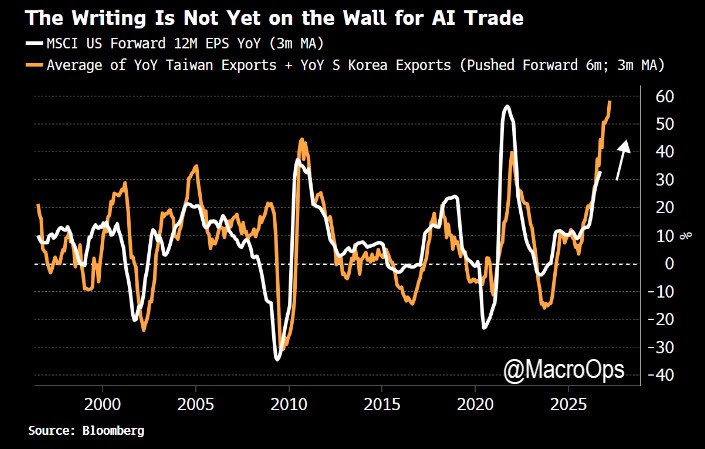
6. It’s all one trade, and one of the best early indicators of a potential trend change is monthly export data out of Taiwan and South Korea (chart from BBG’s Simon White).
7. My teammate Dean Christians put out a couple of bangers last week. Dean notes:
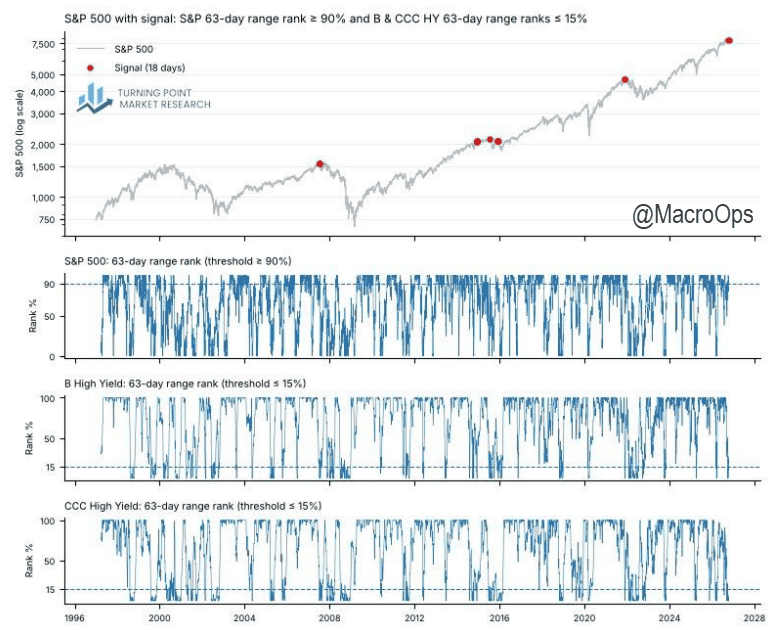
“The following chart highlights instances when CCC- and B-rated high-yield bonds fell to the bottom 15th percentile of their respective 63-day ranges while the S&P 500 remained in the top 10th percentile. Although rare, this divergence between credit and equities has occurred near major stock market peaks. Notably, even higher-rated BB high-yield bonds are trading below the 15th percentile of their range.”
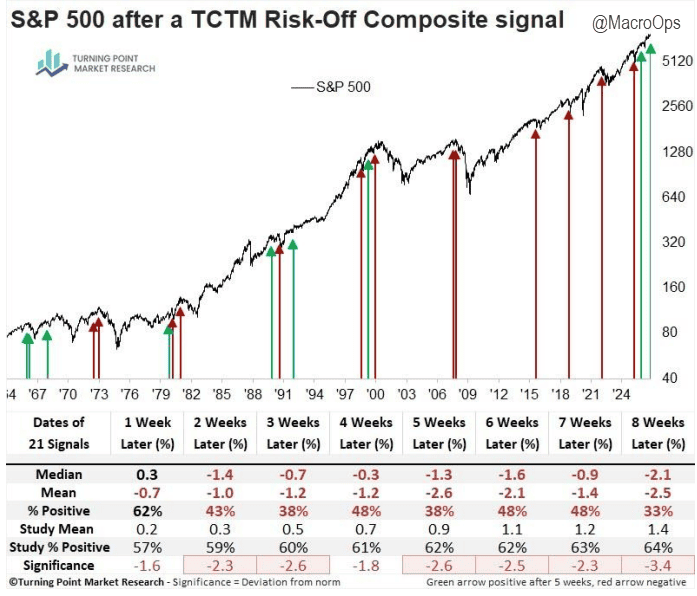
8. Also from Dean: “For only the 30th time since 1929, the TCTM Risk-Off Composite has triggered a warning, signaling narrowing market participation and increased vulnerability to a countertrend pullback in the S&P 500.”
Our current base case is for continued rotation and sideways chop and vol here, though we’re staying nimble.
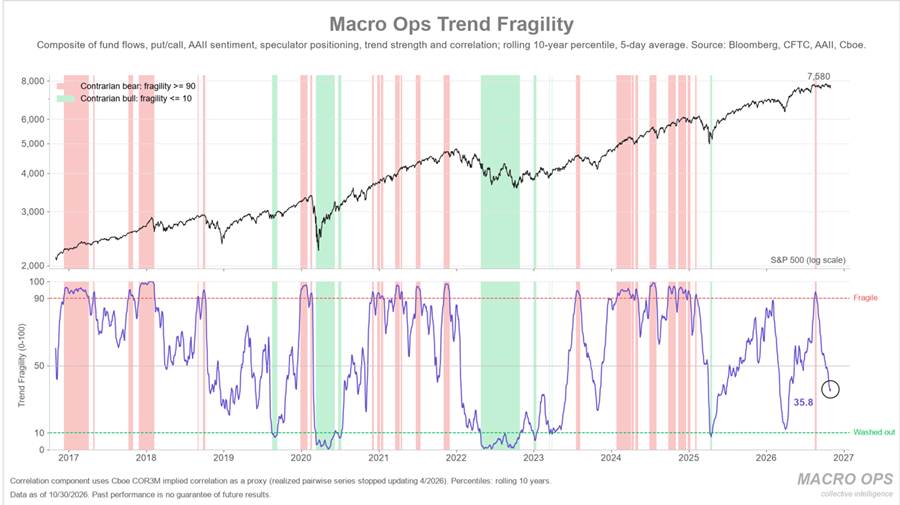
9. Positioning and sentiment. GS reports US long/short hedge fund net exposure fell 3.2 points, the largest weekly drop since Liberation Day, to the 0th percentile across 1-, 2-, and 5-year lookbacks. TMT saw its largest weekly net selling on record. Gross exposure, however, held at 213.9% (83rd percentile over three years). Funds have “gotten less long,” per GS, not materially smaller. They also report six straight sessions of AI-stock selling, with cumulative selling matching late July’s intensity and the largest since March 2022 (-3.0 z-score).
DB’s broader equity positioning measure remains modestly overweight (0.17sd, 51st percentile), but that masks a sharp divide between underweight discretionary investors (-0.36sd, 24th percentile) and heavily positioned systematic strategies (0.81sd, 86th percentile). BofA’s Bull/Bear indicator’s active sell signal has ended.

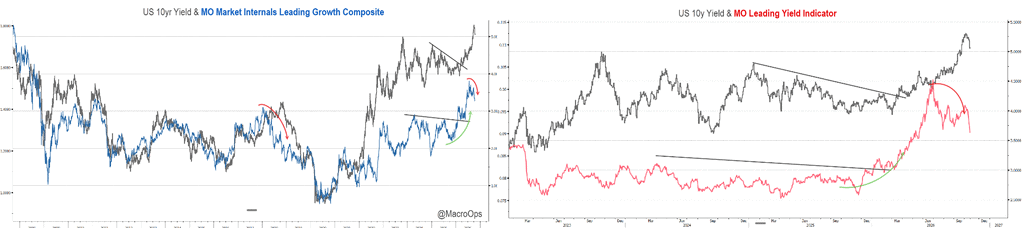
10. A few months ago, in HIGH GEAR: A NEW ECONOMIC REGIME… I laid out the case for accelerating US growth and a breakout in rates. Below are two of the charts I cited in that report. I still believe rates are ultimately headed higher, but these indicators point to a continued near-term pullback in yields, which should give equities some additional relief.
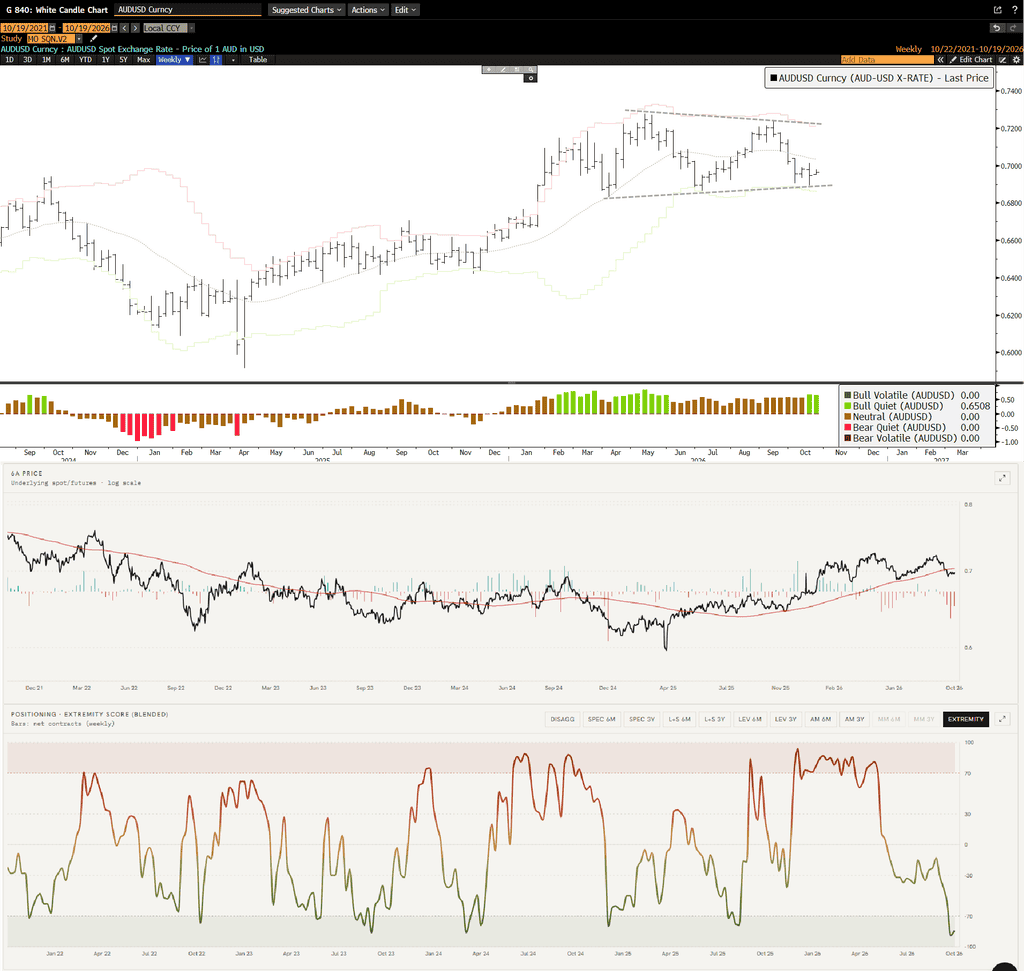
11. There’s not much I like in this environment, though I’m seeing some tactical opportunities in FX. Last week we got long GBPUSD as it reversed off the bottom of its long-term sideways range. I’m considering a similar setup in AUD (weekly chart below), which has seen a big positioning flush.
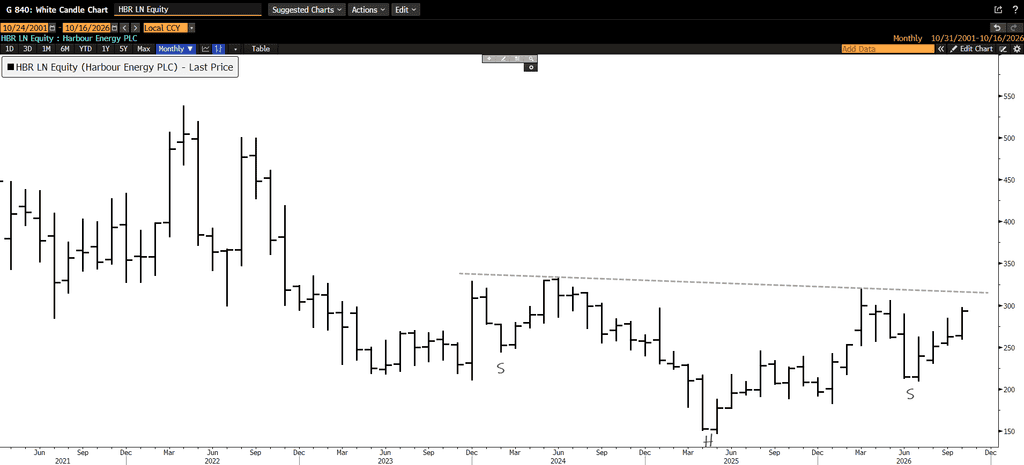
12. One of my favorite equity names right now is Harbour Energy (HBR.LSE). Brandon wrote it up for the Collective the other week, arguing it’s deeply undervalued at ~$9/boe of proven reserves versus ~$18–21/boe for peers. He sees a shift toward lower-tax production lifting cash flow even with flat output, which supports debt reduction and shareholder returns. His bull case implies ~$11/share based on 7× projected 2028 free cash flow at $90 Brent. Chart below is a monthly.
Thanks for reading.