Key points:
- The energy sector retained the top spot in the latest S&P 1500 rankings
- Several industries within technology showed improving trends
- Groups influenced by oil and rates continue to exhibit weak trends
Sector leadership holds steady
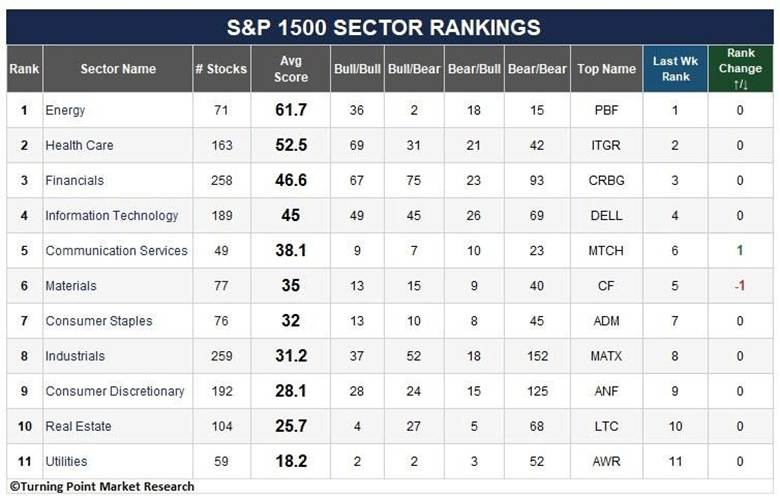
Sector leadership remained largely unchanged last week, with energy retaining the top spot and communication services and materials swapping positions. That stability at the sector level masks a continued deterioration in the underlying opportunity set. The percentage of stocks showing bullish short- and long-term Dual Trend signals has declined for three consecutive weeks, falling from 27% to 25% to 22%.
This deterioration reflects the broadening impact of higher oil prices and interest rates on more stocks. Now, with AI leaders calling for a slower, more safety-focused pace of frontier AI development, technology—which had been showing signs of improvement—could face another headwind, adding to an already difficult market environment.
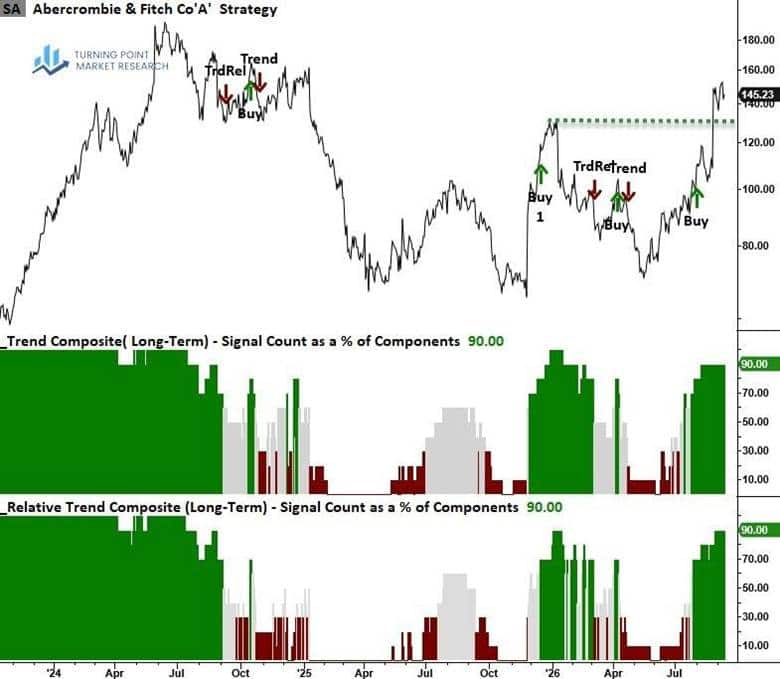
Several of the top-ranked stocks in each sector were worth highlighting, including Archer-Daniel Midland (ADM) and Matson (MATX). However, Abercrombie & Fitch (ANF) has the most compelling setup. The stock recently broke out of a year-plus basing pattern following solid earnings, even after backing out the benefit from the tariff refund. ANF is now digesting those gains, and as long as it remains above the $130 breakout level, another advance could be in the cards.
While the backdrop for consumer-oriented stocks remains challenging given elevated oil prices and Treasury yields, any relief on either front could provide a tailwind.
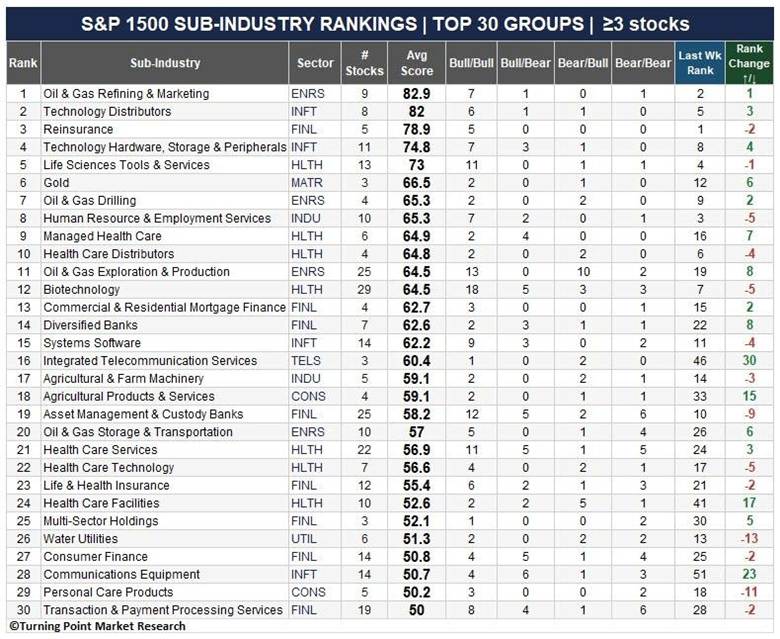
Oil & gas refining & marketing rose to No. 1 overall as crude oil prices helped lift several energy groups in the rankings. More interesting was the improvement in technology, where three of the four technology sub-industries ranked in the top 30 moved higher. Communication equipment was the standout, jumping 23 spots—the second-largest gain among the top 30. That said, the rankings predate weekend comments from several AI leaders advocating a slower, more safety-focused pace in developing frontier AI models.
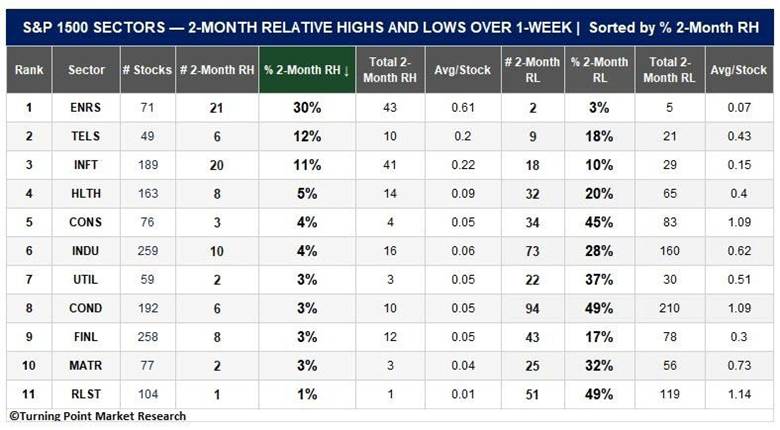
The energy sector once again led all sectors in two-month relative highs, with 30% of its constituents reaching a new high over the past week. However, that was down sharply from 54% the prior week, indicating that the pace of relative breakouts has slowed. This may signal that oil stocks have run up too far, too fast, and are likely to consolidate.
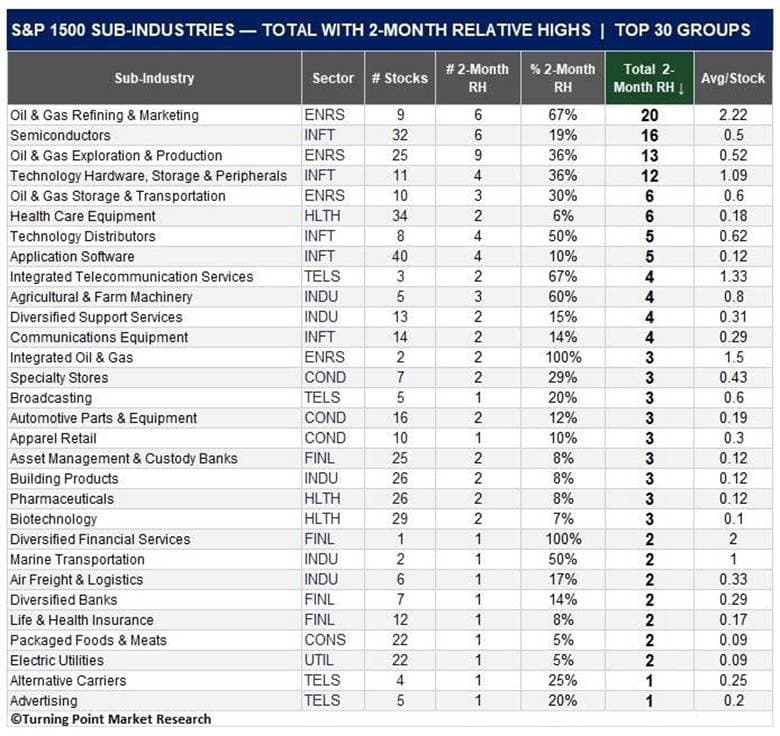
Across sub-industries, energy and technology dominated the two-month relative high breakout list, accounting for seven of the top 10 groups. Semiconductors ranked No. 2 overall, led by Skyworks Solutions (SWKS) and Qorvo (QRVO), both of which registered a relative high on all five trading days last week.
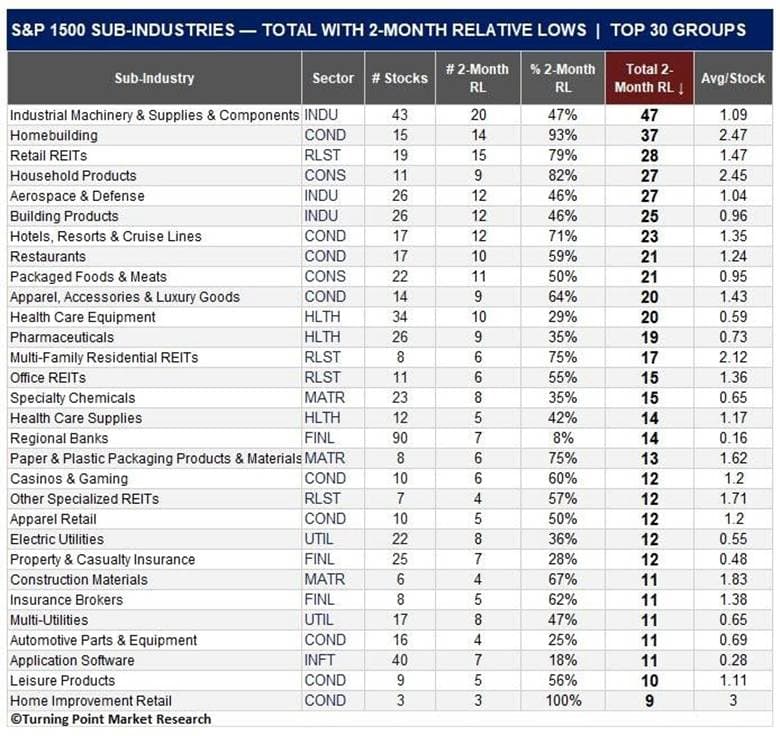
As with last week, consumer and rate-sensitive groups dominated the list of sub-industries with the highest proportion of two-month relative lows, as higher oil prices and yields continued to weigh on these areas.
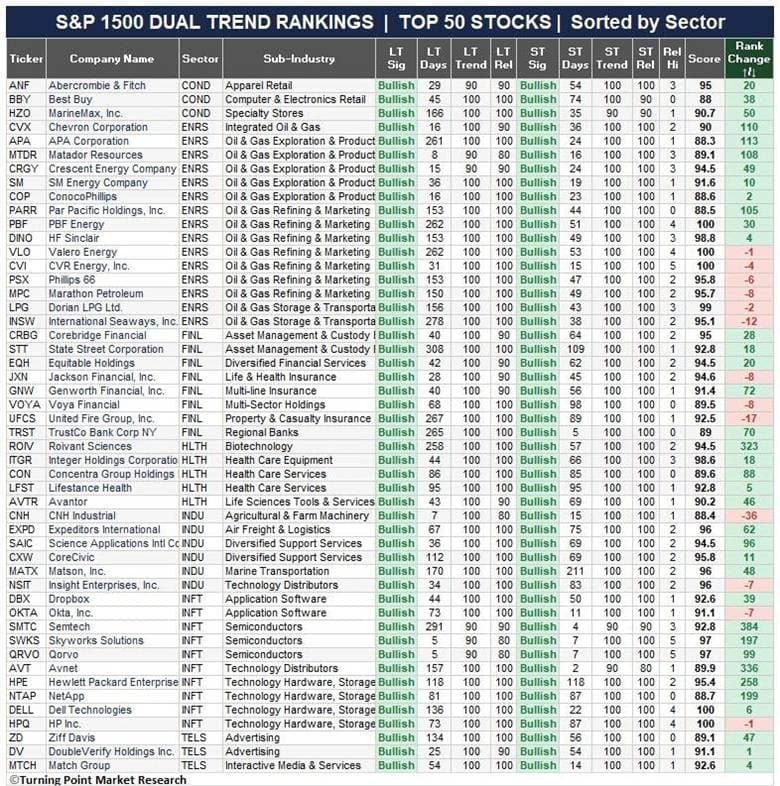
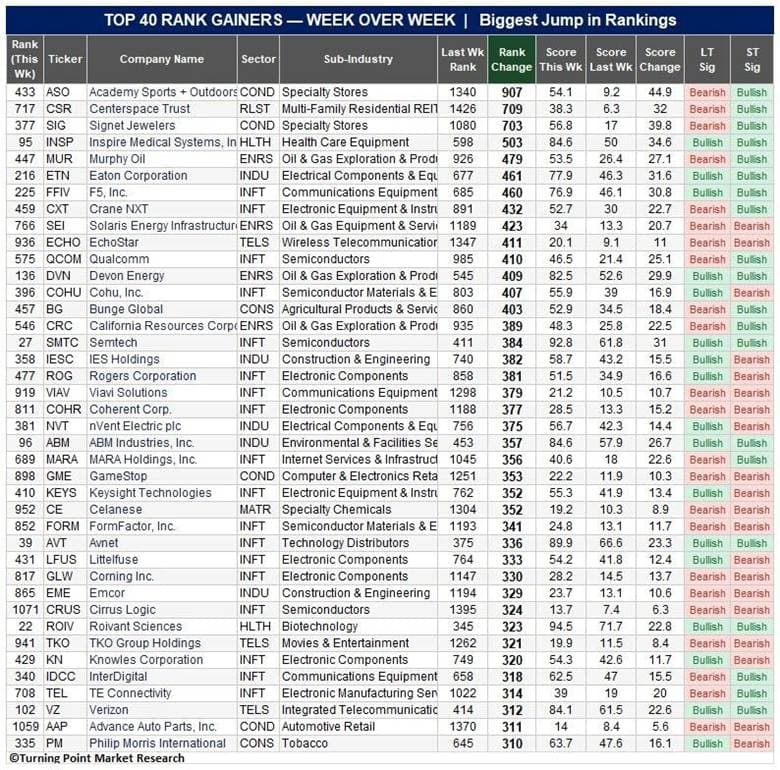
Dell Technologies ascended to No. 1 among all S&P 1500 constituents. Technology stocks were also well represented among the biggest ranking movers, with Semtech posting the largest gain, jumping 384 spots.
Roivant Sciences (ROIV) was another notable mover, rising 323 spots after positive Phase 2 results for mosliciguat, its inhaled treatment for pulmonary hypertension associated with interstitial lung disease (PH-ILD).
Technology dominated the biggest week-over-week ranking gains, accounting for 18 of the 40 largest jumps among S&P 1500 constituents. Within the sector, F5, Inc. (FFIV) led the way, climbing 460 spots.
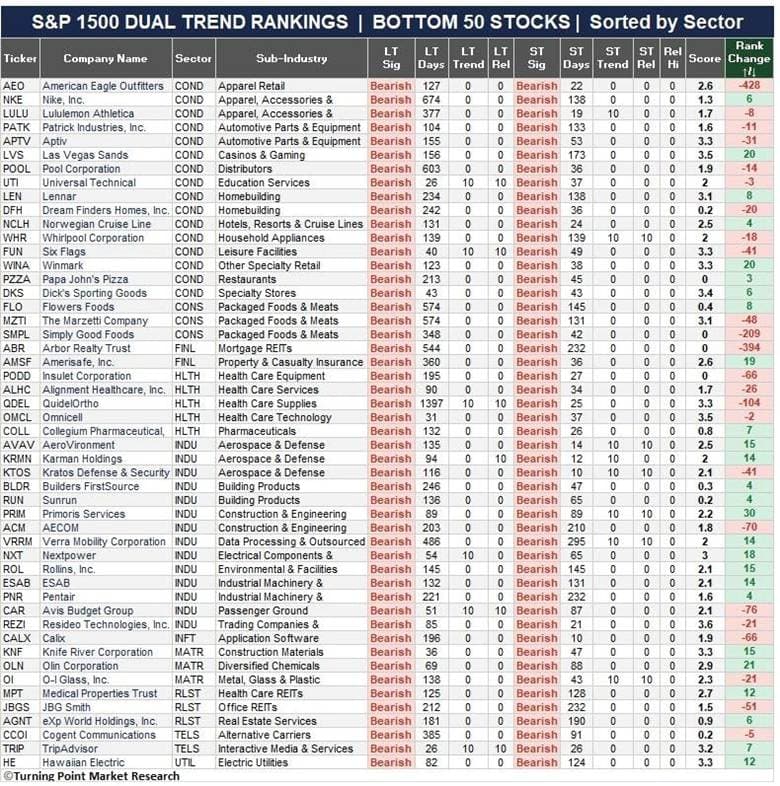
Consumer discretionary and industrial stocks continue to account for the largest share of names ranked in the bottom 50 of the S&P 1500.
Remember, successful investing is not only about what you own, but also what you avoid.
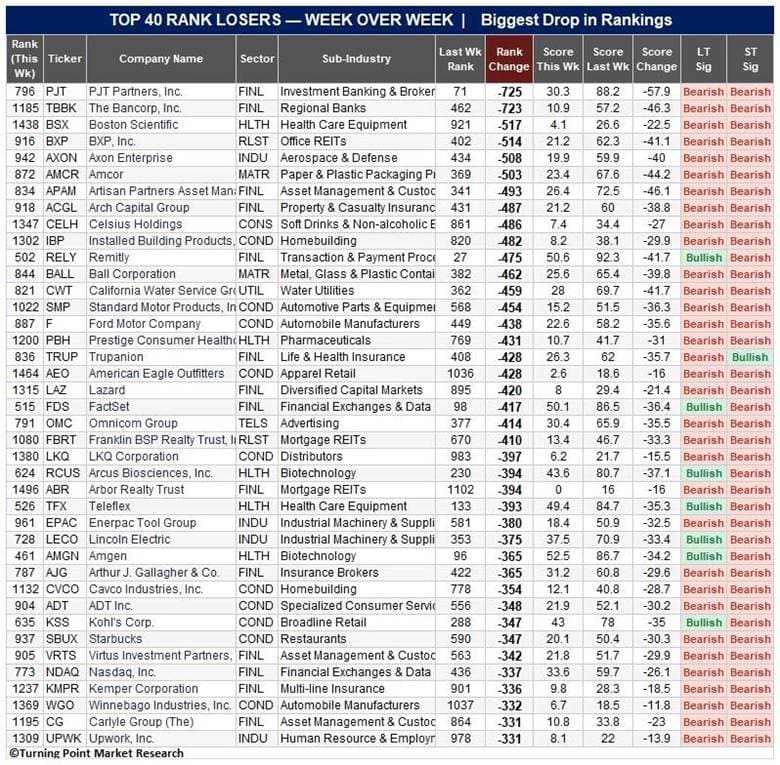
Among the 40 stocks with the largest week-over-week ranking declines, financials accounted for the largest share, followed by consumer discretionary. The declines within financials were relatively broad-based across sub-industries, suggesting there was no clear group-specific theme. Carlyle is one name worth watching, as it is approaching a potential break of support within what appears to be a rolling top.
Energy leadership
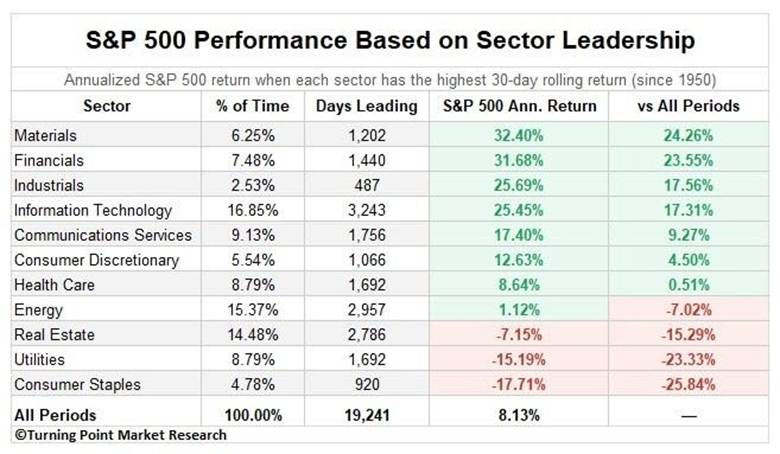
When energy leads the market, as it does now, the S&P 500 has generated an annualized return of just 1.12%. While not the worst among the 11 sectors, that is well below average.
What the research tells us…
With technology taking a tumble today after headlines from AI leaders over the weekend, the market environment is likely to remain challenging for now. Even energy, the market leader, appears fatigued and in need of consolidation. With cyclicals facing pressure from higher rates, a potential Fed rate hike, seasonal headwinds, and the election approaching, maintaining a more neutral stance across sectors and industries may be prudent for now.