There’s something different about this Long Pull Report … can you tell? We’ve finally grown up and “professionalized” it! Macro Ops turns TEN this year, which is about 65 years in the online publishing business. We deserved a makeover.
Big shout-out to Mike G for making this happen. We hired him for this reason (and his classical charting skills!) and are thrilled with the results. We hope you guys like the new look, too.
Last week, I explored our equity book’s metals and mining positions and outlined trade/risk management plans for the week(s) ahead (read here). I did this for two reasons:
- I wanted new Collective members to gain a better understanding of the portfolio and learn how we think about risk management in real time.
- It’s a public journal to hold me accountable for adhering to proper risk management protocols.
The piece achieved both goals as we swiftly took profits this week in most of our metals and miners without relinquishing too much open profit.
This week, I review the Energy/Oil side of our book, the one thing that’s kept the portfolio’s head above water the past week.
The Energy Basket: Producers (18.50% Notional)
We own three companies in our Producers basket: Valeura Energy (VLE.TO), Exxon Mobil (XOM), and Vista Energy (VIST). XOM is our largest position at 8%, followed by VLE and VIST at 6% and 4.43%, respectively.
Below is a 1M performance graph comparing our names to crude oil and the most relevant ETF thematic (XOP).
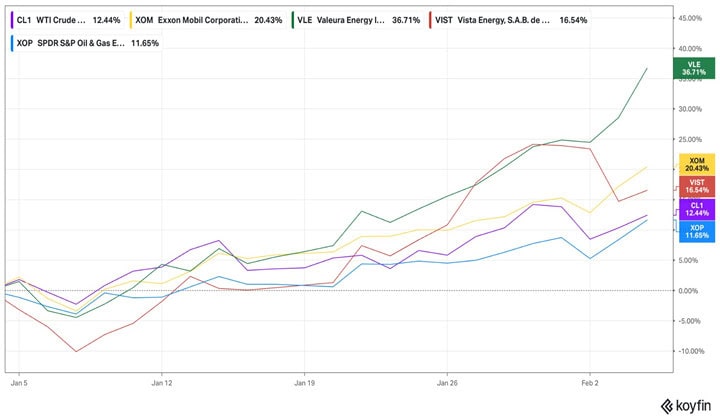
Our basket has outperformed both the underlying commodity and the XOP ETF. We own the relative-strength leaders using our Trifecta Lens Framework. Each name met our Three Main Criteria:
- Fundamentals: Discount to future value (cash flows, replacement cost, peers, cycle averages).
- Technicals: Breaking out of bases or making new highs and outperforming the commodity + thematic ETF.
- Sentiment: Everyone still hates oil.
Exxon Mobil (XOM): A Fat Pitch In A Mega-Cap E&P
We bought XOM on January 13th for a 7.72% initial notional position. I had stalked this position since October 2025 (see tweet below).
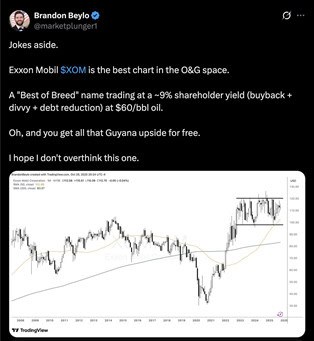
The XOM trade highlights the value of our Trifecta Lens approach to markets and trading. Oil had been “the value/contrarian” trade for all of 2025. But it never worked. It stayed cheap and whiplashed knife-catchers into losses.
We didn’t buy oil names until we received the Technicals green light, which happened around December 2025 – January 2026. XOM met our Trifecta Lens Criteria on January 13:
- Fundamentals: 9% shareholder yield at $60/bbl oil, Guyana upside for free, and a world-class management team.
- Technicals: XOM broke out of a 3YR base to new ATHs. ➢ Sentiment: Everyone still hates oil.
There are three main levers to XOM’s value creation over the next 18-24 months: Guyana production ramp, shareholder returns, and higher oil prices.
Guyana: A Monopoly on The Next Great Basin
XOM is the “designated operator” and 45% owner of the Stabroek Block — the premier block in Guyana.
Here’s a snippet from OEDigital.com:
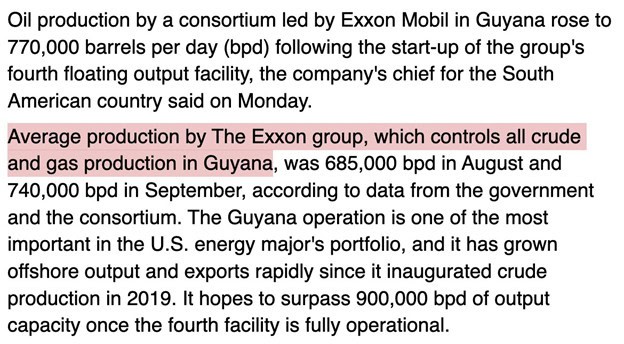
I don’t know … it seems like XOM is a strategically valuable part of Guyana’s oil production infrastructure. This week, the company acquired the FPSO One Guyana vessel for $2.3B. What’s XOM worth to the future of Guyana production? Probably a lot.
Guyana is important because it has low breakevens (~$35/bbl). Lower breakevens mean higher profit margins and a more durable business through the cycle.
XOM currently produces ~900Kbbl/d from Guyana with plans to hit 1.7Mbbls/d by 2030. That would amount to 30% of XOM’s total oil production coming from low-breakeven Guyana. Remember, that’s 30% high-margin production.
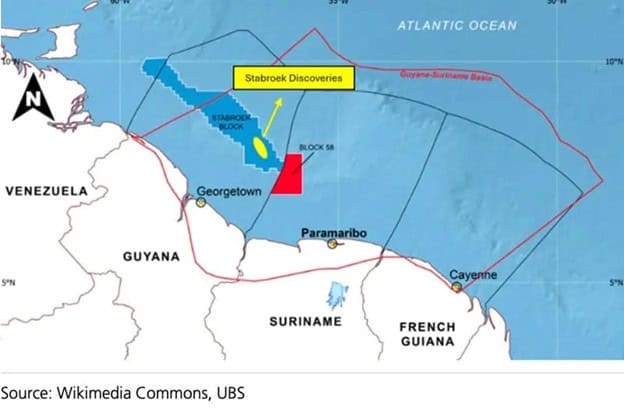
According to Sven at Undervalued-Shares.com, “Guyana is blessed with relatively low production cost. Even at an oil price of just USD 65 per barrel, the Stabroek assets are expected to generate annual free cash flow of about USD 3.9bn between 2026-2030 and USD 5.5bn between 2026-2036.”
So you have a mega-cap company that owns 100% of oil production in the next greatest oil-producing region, which is transforming its production profile to lower breakeven and higher-margin barrels, while generating substantial FCF at potentially trough oil prices.
Shareholder Returns: Buybacks & Dividends
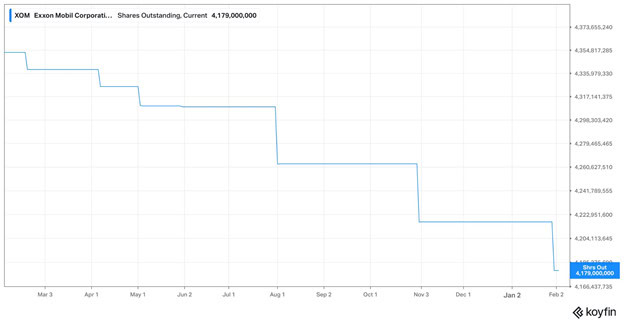
Buybacks are the second lever for shareholder returns. XOM is repurchasing ~$20B in stock annually on a run-rate basis. At that rate, XOM could buy back ~18% of the share count and add ~$52/share to EPS.
The company also pays a dividend that has grown ~3.30% annually over the past 10 years.
Multiple Expansion: Higher Margins + Higher Oil Price
Here’s how I think about XOM’s multiple expansion potential. The company should generate higher margins as it moves more production to Guyana-based sweet, light oil.
This should allow investors to assign a higher multiple to XOM, as it is more cash-generative and better positioned to manage lower oil prices.
The good news is that XOM increases margins without a higher oil price. What multiple should investors pay if oil prices reach $75, $85, or $100/bbl? 20-25x? That doesn’t seem unreasonable for a best-of-breed high-margin producer with a dominant position in the fastest-growing oil region globally.
Let’s head to the tape.
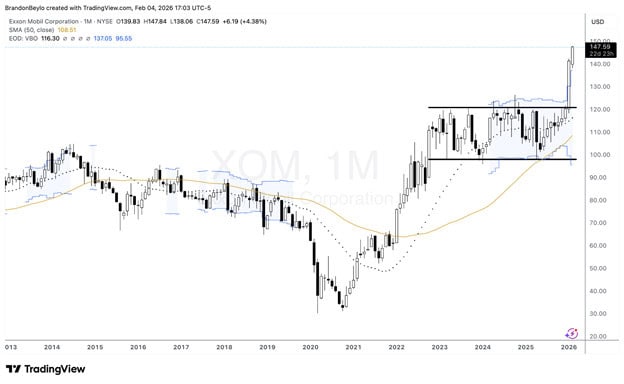
I expect a pullback within the next few weeks, given the quick run from the initial breakout point. However, I love our cost basis and notional size. If anything, we will add DOTMs on pullbacks if there’s good value. File this under “do nothing but wait.”
Valeura Energy (VLE.TO): Leaders Lead
VLE is up 350% over the past three years, and remains one of the cheapest E&Ps I can find.
It’s also one of the best turnaround stories I’ve seen. CEO Sean Guest took a struggling Turkish gas explorer and, in under two years, transformed it into Thailand’s largest independent oil producer by acquiring assets from companies in bankruptcy or exiting the region.
For some reason, financial intelligence platforms (including Koyfin and BBG) do not capture VLE’s capital structure. The company has an $800M market cap with $305M net cash (no debt) as of its most recent reporting period. Yet on Koyfin, you’ll find $224M in cash with $92M in debt.
In other words, the company’s actual Enterprise Value is $495M versus Koyfin’s $670M.
VLE generated $151M in FCF last year for a ~31% FCF yield in the current oil price environment. So why the massive discount?
First, not many investors think of “Thailand” when they want oil exposure. They think the Permian, Guyana, or other common offshore jurisdictions.
The second reason is redevelopment risk. VLE is developing the Wassana field, which is expected to reach first production in Q1-Q2 2027. If successful, it would extend their portfolio’s production life and add significant terminal value. However, I believe that risk is priced in at the current EV.
Speaking of the current EV, VLE has ~40% of its market cap in cash and no debt. There’s so much they can do with that cash. They can push for faster development in Wassana, buy back a large chunk of stock, pay a massive special dividend, or acquire another player in the region to build scale (reminds me of APM, honestly).
Either way, I trust the CEO to make the right decision. He took an essentially bankrupt company and turned it into a CAD 1B business.
Now check out the chart.
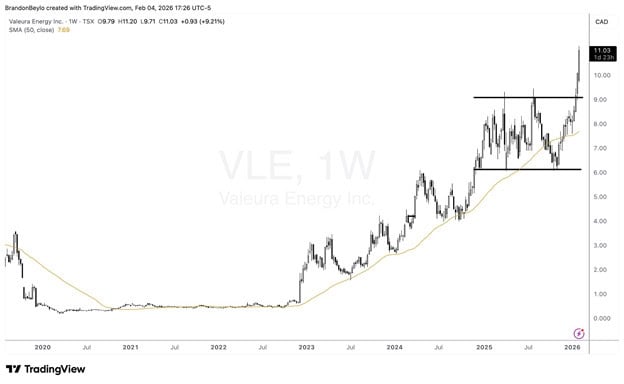
A bullish close this week would mark five consecutive bull bar closes on the weekly time frame, with the past three being at new ATHs.
I like our position size here. If anything, we have room to move stops to reduce risk (currently sitting at CAD 7.59/share).
Vista Energy (VIST): An MO Favorite
VIST is our Argentinian E&P with a dominant position in the Vaca Muerta, the world’s second-largest shale gas and fourth-largest shale oil reserve. Here’s the quick pitch on why I bought VIST (again … never should’ve sold it, I know). Since 2018, the company has:
- Increased production 5x
- Reduced lifting costs by 68%
- Increased proved reserves by 9x
- Increased Adj. EBITDA by 7x
The company recently outlined its plans to achieve 180K-200Kbbl/day production by 2030 (a 75% increase from ~114Kbbl/d today). That’s an aggressive target, but the company has the assets to do it.
VIST controls ~229K acres in the Vaca Muerta with a well inventory of 1,650 identified drilling locations. At their current pace, VIST could drill for the next 25 years before needing to look elsewhere.
Then there’s the recent (as of this week) Bandurria Sur acquisition by Equinor, which is already producing ~80 K bbl/d (see below).
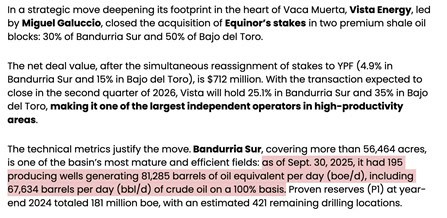
I think 200 K bb/d is achievable. What does that mean for cash flow and valuation? VIST generates ~$40 netbacks as of Q3 2025 results and current oil prices (~$65/bbl as of the latest report).
200Kbbl/d production and $75 oil gets you ~$5B in revenue ($71 realized price) and ~$3.7B in EBITDA. You can buy VIST today for $8.6B EV (or 2.3x 200kbbl/d EBITDA).
What should VIST be worth if they hit that target? At least 5-7x EBITDA. But more if Milei maintains his Argentinian PR magic. If investors recognize the Vaca Muerta as “the next great onshore basin”, why shouldn’t VIST – which holds a dominant position in that basin, generating substantial cash flows – trade at 7-10x EBITDA?
VIST is a 3x from today’s prices at 7x 200Kbbl/d EBITDA.
Let’s head to the chart.
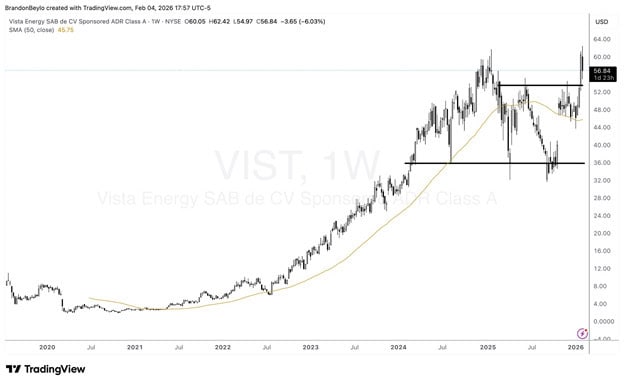
The stock briefly closed at new weekly ATHs before retracing after the Equinor transaction. We bought the failed H&S reversal (worked with SILJ!) and have an initial stop at $46 (the midline on the weekly time frame).
I sound like a broken record, but I like our position size and current stop loss. There’s room to increase our size at 4.45% notional, which we will do when the opportunity arises.
What We Have is Nice … But I Want More Exposure
My friend @PurpleDrinkCapitalLLC on Twitter likes to say, “when energy works, it really works … the flipside is that nothing else tends to work during that time.”
I’ve thought a lot about that comment this week. If energy is starting its bull run, nothing else may work in the meantime. And if that’s true, maybe we shift most of our equity book to oil/oil-adjacent plays and wait it out?
With that in mind, I’m scouring the RS Inflection and Composite screeners for new energy plays to add to the portfolio. If you have any ideas you think we should buy, please let me know on Slack! I love hearing new ideas from you.
Until next week!