We’ve got a shorter Long Pull this week as my daughter caught a viral cold/bug and hasn’t slept through the night in almost three days. I remember some people telling me, “Oh yeah going from one to two kids was way easier than going from zero to one.”
To those people, I ask, “Are you on drugs?”
I’m splitting my time between toddler duty while my wife quarantines with our eight-week-old and monitoring markets/our portfolio and thematics.
The good news is we hold lots of cash and only 38% equity exposure. The bad news is that we’re in the middle of a 14% drawdown from our YTD highs of ~60%. Whenever we experience drawdowns of this magnitude, I like to step back and review our thematics on both fundamental and technical bases. It “grounds” me, so to speak.
Between A Rock & A Hard Place
I told Alex in one of our meetings this week, “I feel like there’s tail risk wherever we go.” And no matter what we do, we expose ourselves to the other side of the tail.
Take oil, for example. We’re sitting at $100/bbl with the Strait closed for 80+ days (and counting). There are E&Ps (explorers and producers) trading at <4-5x cash flow at $80-85/bbl. XLE and OIH are making new highs, the sector remains under-owned, and you can argue that the floor oil price should be higher going forward (SPR re-fill, strategic stockpiling, pent-up demand, infrastructure destruction, etc.).
Those are some of the reasons we have 30% exposure to oil and gas-related equities.
The flip side is that we wake up tomorrow to a real peace deal (not just random tweets), oil gaps down 10%, and our energy basket declines by 12-18%.
Now do the same thing with AI/tech/data center plays. This is one of the strongest thematics in markets. NVDA keeps beating earnings estimates, raising guidance, and expanding the AI/chip bubble. Investors are constantly finding new “AI bottlenecks” to bid 100-200% in a month, and most chip stocks have bounced off their midlines in strong bull trends.
Those are some of the reasons you’d want to stay long (or get back into) the AI/tech/data center trade.
However, we could also wake up tomorrow to an escalating war with boots on the ground, increased bombings, and a Strait closure that could last through the summer.
That would probably send the Qs down 3-5% and all the high-beta AI/data center names down 10-15%.
In other words, that’s why we hold lots of cash and will be slow to add new net risk (i.e., adding positions that increase our net actual at-risk).
Alright, on to our quick metals-and-miners thematic check-in.
Metals & Miners: Potential Failed Breakdowns?
We exited our entire metals and miners basket this week amid the continued sell-off in bonds and a relatively strong USD (though it still remains range-bound).
As I mentioned in the trade alert, we are still long-term mining bulls as they will benefit from two main drivers:
- The Debasement Trade: benefits our gold and silver miners.
- The Return To Matter: Exponential growth of token consumption meets the physical constraints of raw material supply growth.
Let’s start with PMs.
Gold & Gold Miners
Gold miners (GDX) are trying to hold their third higher low since November 2025 (see chart below).
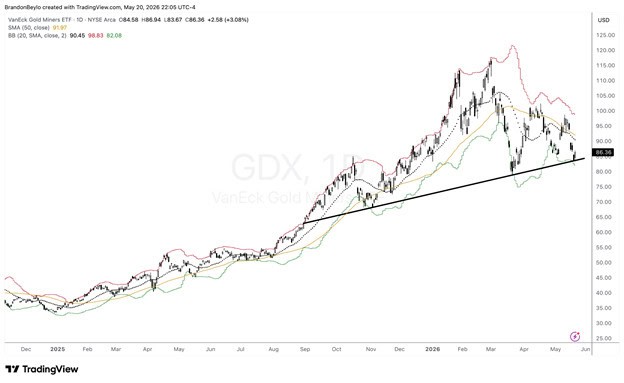
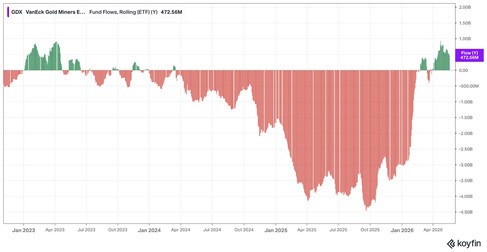
If it holds, it gives us another potential long entry with tight risk (the March 20 lows). Though I’d like to see fund flows flip negative again, as it would give us a confirming signal on positioning.
Gold is trading above its $4,300-$4,550/oz support range. This is a decent tradable bottom. The only problem is positioning data doesn’t meet our Trifecta Lens requirements. Large and small specs are both 90%+ long on the 26- and 260-week time frames (see below).
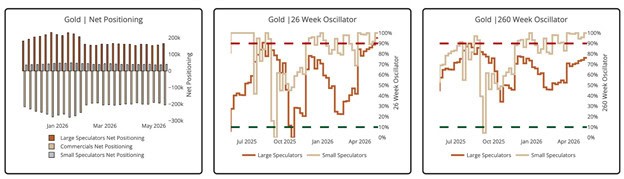
Nothing to do here so far.
Silver & Silver Miners
There’s nothing to do in Silver for now, either.
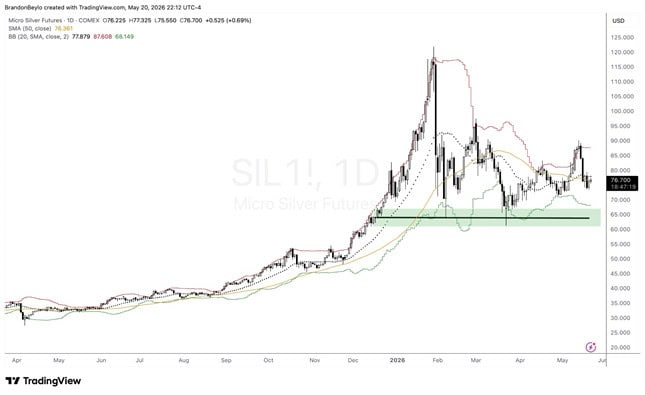
Poor Man’s Gold remains rangebound between $63-$90/oz. I’d be interested in adding back around support or on a VBO from further compression.
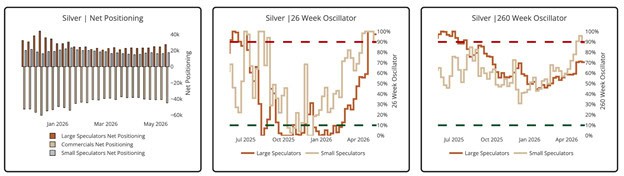
The CoT data resembles gold and doesn’t give us a reason to get long (see below).
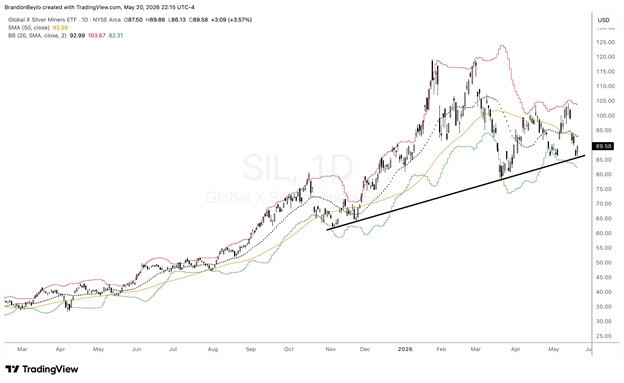
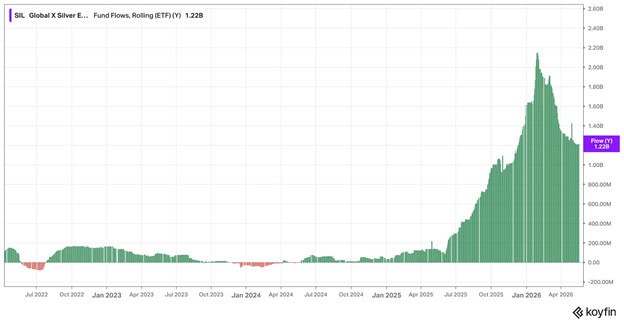
I do like the chart for Silver Miners (SIL). Like gold, it’s attempting to make its third consecutive higher low in this uptrend.
And while fund flows have declined significantly from their Jan-Feb 2026 highs, they remain highly crowded relative to the January 2024 lows.
Copper & Copper Miners
Copper Miners (COPX) has one of the strongest charts in the metals space. The ETF closed below the 50D yesterday, then shot right back above it today, closing on its highs. It’s trading near the lows of its right shoulder in a four-month inverse H&S continuation pattern (see below).
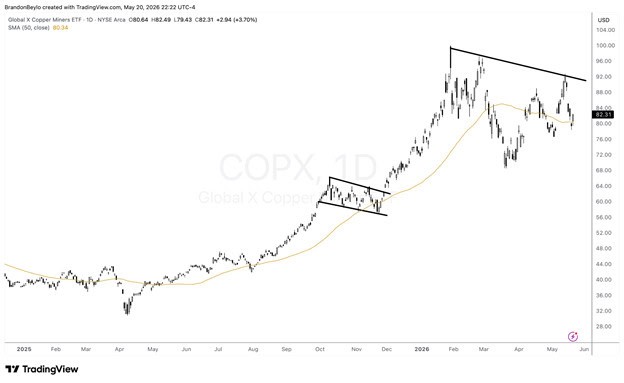
You could establish new longs with a stop below $76 or $68/share. Let’s check in on the underlying commodity.
Copper broke out of its five-month rectangle last week, then retraced the entire breakout before finding support at the breakout level (see below).
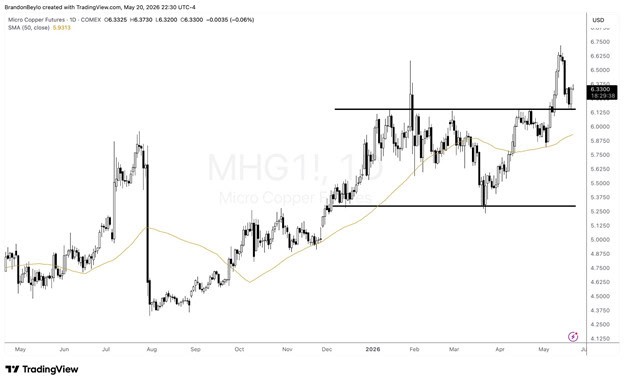
While you could enter a long here at the midline with a stop below the May 1 lows, positioning would say otherwise.
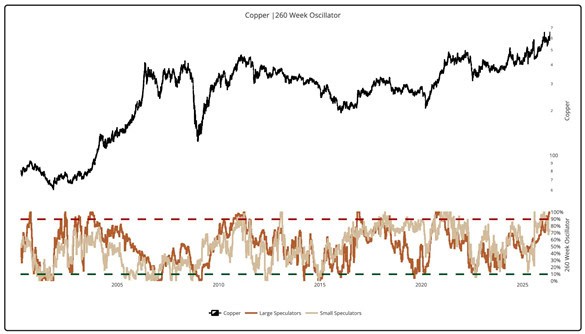
Large and Small Specs remain elevated (75%+), which has historically been a bad time to buy copper.
I want to highlight that not reading the positioning data was an error in my trading plan. I should’ve checked positioning before increasing copper exposure via RIO and FDY.TSX. We should’ve been trimming our copper exposure into this increased Spec positioning. My error cost us PnL, which I hate. I won’t make that mistake again.
Rare Earths (REMX)
Rare Earths sold off ~16% from its highs in preparation for the Trump/Xi meeting last week. The only problem is that nothing really happened from that meeting regarding rare earths. No big, beautiful deal. No agreement between countries to buddy up and share resources again.
In fact, China tightened its grip on the REE supply chain today (emphasis mine):
“China is rolling out sweeping new controls over its mining sector, expanding regulations beyond rare earths to cover the entire supply chain of strategic minerals just days after a highly anticipated summit between Chinese President and U.S. President Donald Trump.
The official Xinhua News Agency announced Wednesday that the Implementation Regulations of the Mineral Resources Law of the People’s Republic of China will take effect on June 15, 2026. The detailed rules, which implement a broader law passed in 2024, introduce national security reviews for foreign investments in mining and accelerate the construction of strategic mineral reserve facilities, triggering global market concerns over critical resource supply chains.
Most notably, the regulations establish a minimum five-year term for in-situ strategic mineral reserves. After this period, extensions or adjustments will only be approved following reviews by State Council authorities. No entity or individual may mine or encroach upon state-reserved strategic minerals without explicit approval from the State Council’s natural resources authority. The government did not specify which minerals will be covered under the new measures.”
I don’t know. It feels like rare earths sold off not because of anything structural or fundamental, but because AI/tech/semis were hotter.
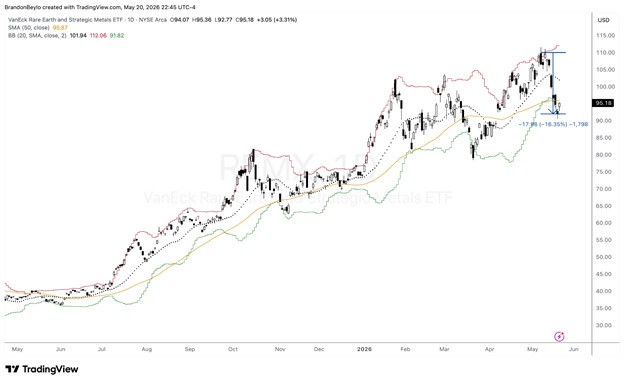
Lots of REE/critical-minerals charts are bouncing off their oversold lows, forming tradable bottoms.
My preferred method of trading this would be to buy REMX on a close above the 50D, with a stop below Tuesday’s lows. You could get tight stops with large notional exposure for little actual risk (20-30bps).
Also, don’t look now, but IDR is 30% off its highs with 15% of its market cap in net cash!

Conclusion: Mistakes Were Made (But We Can Fix Them)
I hate 14% drawdowns. Yes, it’s a drawdown from our high-water mark for the year. But it still hurts. And it hurts even more because we helped the drawdown along by buying when we should’ve been selling/trimming (copper/COPX), adding when we should’ve stayed patient (UAMY second leg), and increasing our net actual risk by taking on more positions.
Things got sloppy. But we can fix them. As Ray Dalio says, there are no such things as mistakes if you have the mindset that every “mistake” is an opportunity to learn and improve.
Looks like we did a lot of future improving these past two weeks!
Stay frosty, Operators.