This will be a shorter Long Pull Report exploring one of our two latest portfolio purchases: Obsidian Energy (OBE).
When I first started at Macro Ops, I obsessed over word count and lengthy research reports. I’d say things like, “I need to write 5,000 words about this company so people think I know it and sound smart.”
Of course, those were always the worst ideas.
The best ideas are the ones that take one page (or less) to explain. These ideas write themselves and “hit you over the head with a 2×4.”
Andean Precious Metals (APM) took a few bullet points to pitch. IDR took less than a page. The Trifceta Lens forces us to condense the best theses into fundamental, technical, and sentiment legs … fitting everything on a 3×5 notecard if possible.
OBE has it all: a simple thesis with 300% upside, hidden assets, aligned management teams, inflecting charts, and a supportive underlying commodity price.
Let’s get after it!
Obsidian Energy (OBE): Textbook Trifecta Trade
OBE is a $833M Canadian heavy/light oil producer with $1.6B in NOLs trading at 0.27x NPV10 with 158 mmboe of 2P reserves, aggressive insider buying, and waterflood upside.
The CEO is a former hedge fund manager-turned-activist with a track record of shareholder success. They recently sold an asset to reduce debt and ARO liabilities, re-upped their NCIB, and sport a ~$30/boe netback and $55/bbl breakevens.
OBE reminds me a lot of Valeura Energy (VLE), a left-for-dead asset with large NOLs, bought by an outsider CEO who started buying back stock at low breakeven levels.
Let’s start with the assets.
The company estimates ~28,900 boed from its two main assets: Willesden Green/PCU #11 (light oil) and Peace River (heavy oil), for a blended netback of ~$30/boed (heavy oil drags on netback due to higher capex).
OBE wants to produce more oil from Clearwater waterflood assets, which is great because waterflooding lowers future decline rates and reduces sustaining capital over time. For example, Tamarack Valley (TVE) has demonstrated waterflood F&D costs of less than $3/boe with recycle ratios above 18x in Clearwater (TVE trades at an EV/2P of CAD 22/share – more on that later).
I like the production roadmap and the plan to shift to waterflood barrels. But the real excitement lies in OBE’s myriad other catalysts.
Catalyst 1: NCIB, Eventual SIB, and Short Interest
The company recently renewed its Normal Course Issuer Bid (NCIB) for 10% of outstanding stock. OBE only has 67M shares outstanding, so each 10% NCIB further boosts per-share NPV and cash flow.
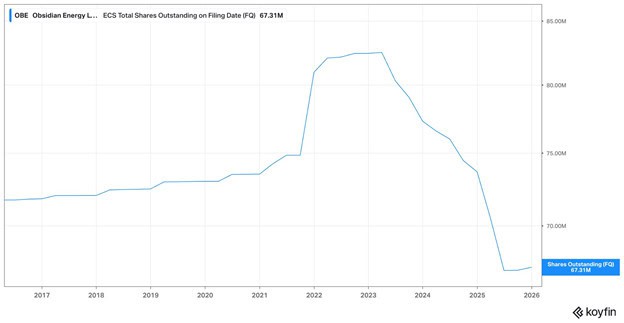
Eventually, the company will generate enough cash flow to do a Substantial Issuer Bid (or SIB) to buy a “significant portion of its outstanding stock.”
And if that wasn’t enough of a share-driven catalyst, there’s also 4.64M shares sold short (see below).
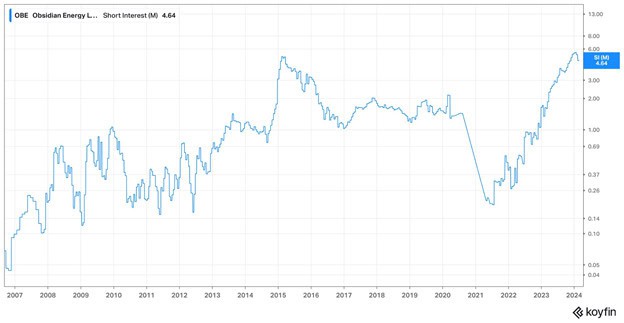
Shorts will cover as the stock rises, effectively adding ~5% to the company’s NCIB (4.64M / 67M shares outstanding) without them needing to do anything.
Catalyst 2: $1.6B in NOLs
“Rule No.1 when investing in natural resource companies: always check for NOLs. Rule No.2 when investing in natural resource companies: never forget rule No.1” – Warren Buffett (probably)
OBE has $1.6B in NOLs, of which $1.34B are immediately deductible. The company also has $612M in realized/unrealized net capital losses (no DTA recognized—only usable against future capital gains) and $45M in SR&ED credits expiring between 2029 and 2036.
Most investors miss this angle because the company carries $190M in NOLs on its balance sheet.
In other words, OBE won’t pay taxes for ten years at $70/bbl WTI. But it gets better. Let’s assume a 23% corporate tax rate on these NOLs. That gets us ~$350M in theoretical value (or ~$5.22/share) fully-diluted and ~$4.50/share for the immediately deductible portion.
For reference, we bought our initial position at a $10.11/share cost basis. That means 50% of our purchase price was covered by the NOL value, leaving the remaining 50% for the operating business (which generates $350M+ in FFO at $85/bbl oil).
Catalyst 3: Hedge Reductions
I have a contrarian view on commodity producer hedging: I don’t hate it. The reason I say that is because I would 100% hedge some of my production if I were CEO of a commodity producer.
Peter Munk, the legendary founder of Barrick Mining, was known for his hedging strategy. And that worked out okay for him.
Here’s OBE’s current hedge book (see below).
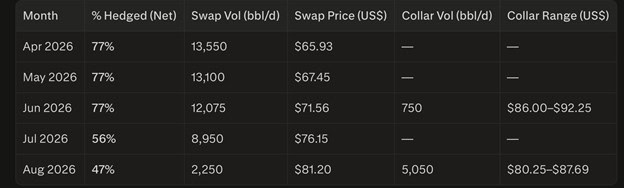
There are two ways to look at this hedge book:
1. “Well, that sucks. They’re only getting $66/bbl today when oil is at $90!
Or
2. “Wow, they’ll be completely unhedged by late summer, and if oil remains around $85/bbl the incremental cash flow will be enormous.”
I prefer the second option. The current hedge strategy protects our downside risk and gives us more time to reap the rewards of future NCIBs/SIBs, waterflood development, short covering, etc.
Catalyst 4: The Re-Rate
I’m not buying OBE because I think they can make a decent profit at $65- $ 75/bbl oil. I’m buying OBE because I think oil will be structurally higher for longer than people think … somewhere between $85-$110/bbl sounds right (I swear every time I open X I see another piece of critical oil infrastructure destroyed).
Let’s assume oil stays around $85/bbl, OBE shifts more production to its waterflood assets (which raises netbacks, reduces decline rates, etc.), buys back 10-25% of its stock, reduces debt, and captures nearly 100% of the higher oil prices due to a reduced/eliminated hedge book.
Where should OBE trade in that scenario? There are three ways to think about this:
- EV/2P: ~$6.20/boe
- EV/Flowing Barrel: $33,944/bbl
- EV/FFO: 2.80x at $85/bbl oil
Now here’s where OBE’s peers trade on similar metrics (see below, calculations performed on April 10th).
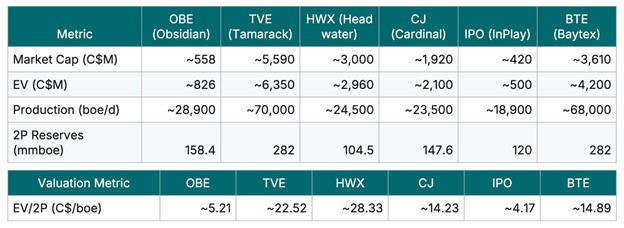
OBE is also cheap on an EV/FFO basis. TVE, HWX, and CJ all trade around 5-10x EV/FFO multiples.
There are legitimate reasons why OBE is cheap relative to its peers (today, at least):
- They produce a mix of light and heavy crude with some natural gas. It’s not as clean as a pure-play light oil producer, which generates higher margins from lower netbacks.
- They don’t pay a dividend, and oil investors love their dividends.
- They had a not-so-great balance sheet before the Pembina asset sale (reduced ARO liability by $390M).
However, all of that changes if the scenario above materializes. If it does, OBE should command a peer-like multiple of 5-7x EV/FFO and $14-$20 EV/2P (~300% upside from the current share price).
The Recap: Value + Catalysts = 300% Upside
Here’s your 3×5 index card pitch:
- OBE generates $300-350M in FFO at current oil prices.
- They use that cash flow to buy back 10-20% of their stock through NCIB/SIB.
- They convert more barrels to waterflood production, increasing netbacks, margins, and profits.
- They use the increased cash flow to buy more stock or reduce debt.
- The market realizes OBE is now a high-margin producer of mostly light oil from waterfloods and assigns a 6x EV/FFO multiple.
- OBE trades at a $2B+ market cap with 57-60M shares outstanding ($35-40 stock).
Oil is back to $95/bbl as I’m writing this sentence. At $95/bbl, OBE would generate ~$430M in operating income or 2.28x its current EV.
It’s just stupid cheap, no matter how you slice it.
Next week, I explore our latest precious metals producer purchase: Kuya Silver (KUYAF).