They say the worst words in investing are “this time it’s different.” I’d argue there’s another five-word phrase that’s just as, if not more, dangerous … “it’s exactly like this company.”
You find an idea, it works really well, and suddenly every new idea looks like that one. Take cars, for example. I love the Lexus GX 550. It’s probably my favorite car on the road. That I love the car so much means it’s all I see when I drive.
How can you not like this car? But unlike this Lexus, great investments are scarce, and that’s the trap.
That said, it’s important to use past successes as “maps” for future investment ideas.
Andean Precious Metals (APM) is a perfect map for future mining investments. I wrote about this in my Podcast Notes with Gavin McCracken (emphasis added):
“I love and hate my APM thesis because it was so damn simple. I didn’t need to do anything except understand this one paragraph:
- Strong balance sheet: $161M net cash
- Cheap price: -$42M EV
- Run-rate production cash flow: $30M
- Realistic metals prices: $30 silver and $3,500 gold
- Insider ownership: 50%+ with insider buying”
Then there’s the “Gavin’s 2x EV/FCF” map (emphasis added):
“Gavin doesn’t “screen” for stocks trading at an EV/FCF of 2x. Instead, he finds companies that are either about to or ramping up production. Then he determines whether he can buy that stock for ~2x (or less) of its run-rate production, assuming a conservative commodity price.”
Kuya Silver (KUYAF) fits both maps. It feels like the next APM because it meets almost all of the same criteria APM did before its move from $0.72 to $10/share.
KUYAF is a Peruvian silver producer ramping up production from 100 tpd to 350 tpd. It bought its mill for $0.50 on the dollar, has $16M in net cash (post mill purchase + investments) and no debt, the CEO owns 7% of the company, and it trades at <1.5x EV/run-rate production at $65/oz silver.
Let’s get after it.
The Assets: Bethania, Camila Processing, and Silver Kings
KUYAF is a bet on four things happening:
- Bethania produces high-grade silver from its current 14.36Moz resource.
- The company ramps production at the Camila Processing Plant to 350 tpd (700 tpd+ long-term).
- Successful drilling outlines 100 Moz+ at Bethania and Silver Kings.
- KUYAF goes from 1-1.5Moz to 2Moz of silver-equivalent production.
If those four things happen, KUYAF is a $1B+ market-cap company. Today it trades for $85M.
The good news is that we only need about 5% of that to make a lot of money here.
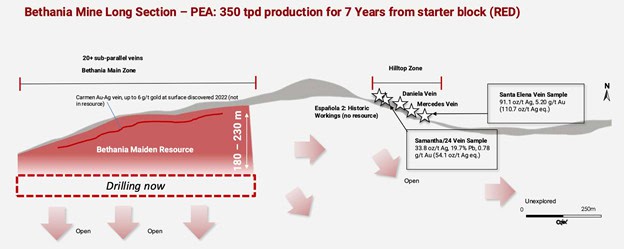
Bethania: 14.4Moz with 0.3% Land Explored
Bethania is KUYAF’s main production asset, located in a major silver-lead-zinc mining district in Central Peru. The deposit’s 2021 Maiden Resource Estimate included 14.39Moz of AgEq (silver equivalent) at 406g/t AgEq grade.
Many mining investors will dismiss that resource as “too small” despite its terrific average grades. But there are two main factors when assessing this resource estimate:
- It only focused on the shallow mineralization adjacent to the existing Bethania mine workings (sub-200m depth).
- It only covered 15 hectares or <0.3% of Bethania’s 4,500-hectare land package.
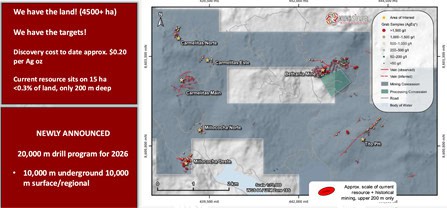
The company has already identified 20+ sub-parallel veins at Bethania and six additional vein systems within 5km.
Even if KUYAF didn’t find another ounce of silver, it could produce for ~14 years at 1-1.25Moz/year throughput.
Remember: you’re not paying for additional exploration success. Look at how much exploration potential KUYAF has within Bethania alone (see below).
Camila Processing Plant: Buying A Mill For $0.50 on the Dollar
I called KUYAF’s CEO, David Stein, last summer when the stock was around $0.33/share. His plan at that time was to leverage toll milling to ramp up production and expedite cash flow, and then eventually use that cash flow to build a mill.
However, and this is the reason I returned to the stock, the company announced the acquisition of the Camila Processing Plant/Mill in January 2026.
Here’s a snapshot of the deal below.
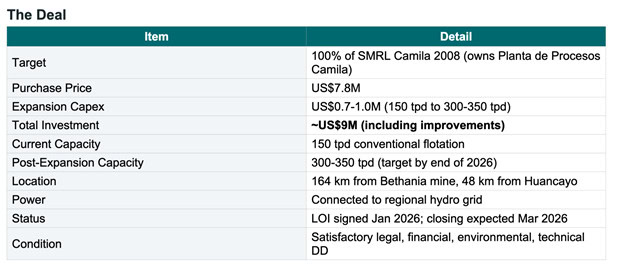
This is where it gets interesting. The 2022 Bethania PEA estimated the cost of building a new 350 tpd processing plant at US$14.2M in initial capex plus a US$3.6M contingency (~$18M). Adjust for inflation, and you get ~$19-22M in replacement cost for a 350tpd mill.
So KUYAF bought its already-operational mill at 50% of its replacement cost. Owning a mill was one of the pillars of my APM thesis. Are you seeing the similarities?
Owning a mill also allows KUYAF to become the toll miller of choice for other artisanal miners throughout Peru (again, just like APM).
Silver Kings: Blue Sky Potential in Tier-1 Jurisdiction
The Silver Kings project is the company’s 100%-owned 13,000-hectare land package in NE Ontario, located within the historic Cobalt, Ontario silver mining district.
I’m marking this at $0 in our valuation, so any drilling success is pure gravy. But there have been some good hits within the package, including:
- 15,372g/t silver over 3.34m at 200m depth
- 639g/t silver over 2.20m
- 23g/t silver, 4.1% cobalt, and 1.1% nickel over 1.74m from surface
I’d expect KUYAF to drill this property after spending as much time/money as possible on Bethania.
The Maps: APM & “Gavin Math” Criteria
Let’s review the APM checklist thesis from earlier with KUYAF’s metrics:
- Strong balance sheet: $16M net cash, no debt
- Cheap price: $69M EV for ramped production of 1.25Moz high-grade, and owned mill
- Run-rate production cash flow: $50M pre-tax profits at $25/oz AISC
- Realistic metal prices: $65 silver
- Insider ownership: 7% with recent buys in January
KUYAF checks all the boxes. Now onto Gavin’s 2x EV/FCF hurdle. Here’s my (very simple) napkin math below.
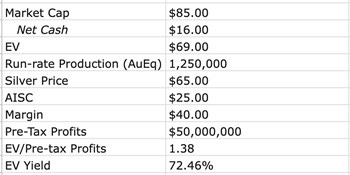
The company trades at a 72% EV Yield at $65 silver, an 80% yield at $70 silver, and a 90% EV Yield at $75 silver. I’m also assuming the high end of KUYAF’s AISC guide, $20-$25/oz.
In other words, this is a “hit you over the head with a 2×4” valuation.
What about the chart?
The Tape: Another Reminder of APM?
Check out KUYAF’s weekly chart below.
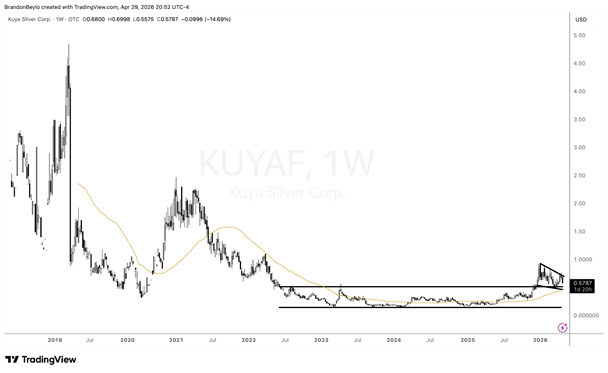
It recently broke out of a 5-6YR base and is forming a bull flag back at its breakout (now support) level. I love this setup: strong breakout with consolidation before the next leg higher.
Now here’s APM’s weekly chart. Notice anything similar?
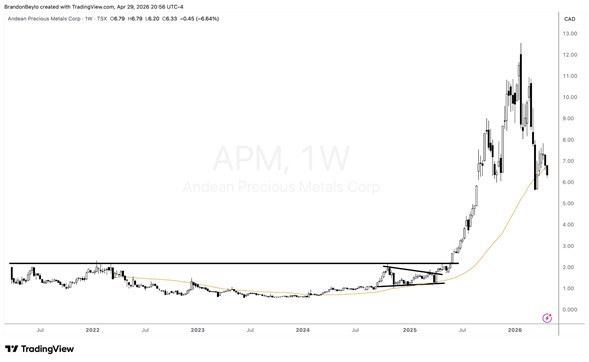
APM experienced a similar breakout-consolidation-breakout pattern after moving through the $0.75- $ 0.80-per-share level. Both charts also show consolidation above/hugging the 50D MA.
Final Thoughts: Soft Intangibles
Two more comments on things you won’t see on income statements, balance sheets, or resource reports.
First, CEO David Stein started his latest investor presentation by saying, “I’m a geologist, but I’m going to do this presentation without mentioning a rock or a mineral. Instead, we’re going to focus on silver and cash flow.”
Second, I didn’t buy KUYAF last summer because I didn’t think David could execute. But he’s proved me wrong. Not only has he done what he said he would do, but he has also exceeded my expectations by buying the mill at 50% of its replacement cost.
Plainly, KUYAF has everything it needs to return 5-10x our money from today’s price.