Happy September, Collective! It’s crazy to think we only have four months left in the year. Time flies when you’re having fun, learning about interesting companies, and interacting with the best online investment community out there.
Since it’s month end, I want to quickly recap our MO Tracking Portfolio performance:
- August: +6.58%
- Q3 2026 (as of August close): +4.30%
- YTD 2026 (as of August close): +50.17%
We’ll take it, but we’re not resting on our laurels, either. There’s still four months of trading. A lot can happen. As always, our job is to stay patient, not do anything stupid, and swing when a Trifecta Lens trade crosses our desk.
Speaking of Trifecta trades … This week’s Long Pull Report argues that data centers have triggered a Trifecta Lens setup.
Importantly, this trade idea highlights my continued evolution as an investor; my journey away from breakout trading and into buying deep pullbacks/stocks bouncing off long-term support ranges.
“It’s not the strongest of the species that survives, nor the most intelligent that survives. It is the one that is most adaptable to change.” – Charles Darwin More on that at the end of the note.
Sentiment/Positioning: Potential Peak Pessimism?
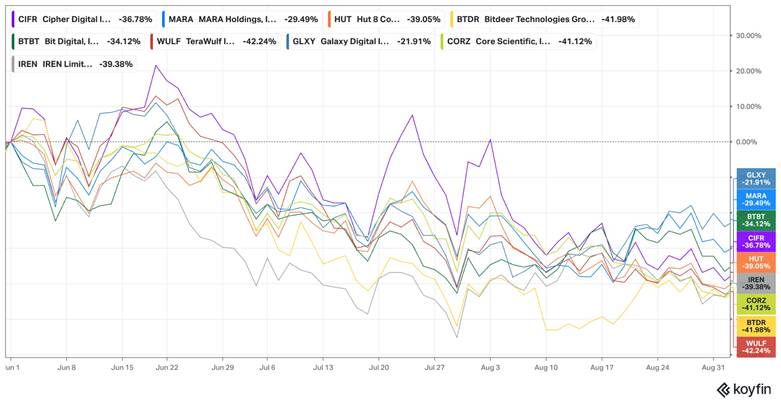
Data center stocks have been some of the worst performing stocks over the past two months. The bitcoin miner ETF, WGMI, is down 45%+ from its June highs. The Global Data Center ETF is down 17% from its June highs (less volatile so the drawdown is still impressive).
Pick your token data center/bitcoin miner play and it’s down 35-45% since June (see below).
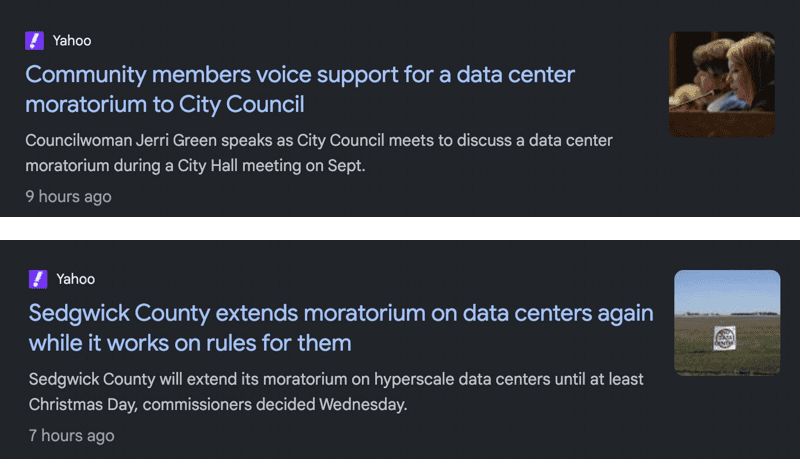
Price drives narrative (as we know). And the narrative around data center companies is horrible. It seems like I wake up daily to a new data center moratorium. Okay, maybe not every day, but it’s enough to get Gavin Baker to personally promote the benefits of data centers on every podcast and tweet.
Check out a few of these headlines just from the past 12 hours.
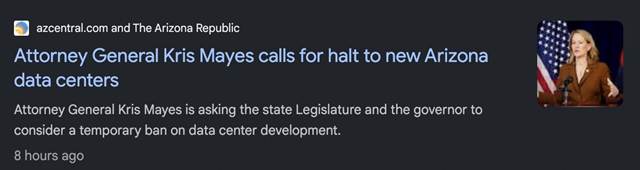
However, I never really believe the sentiment/narrative story until I see it in a Jim Cramer tweet. And the man delivered
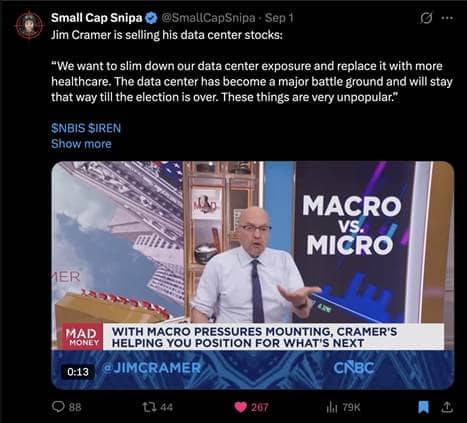
Who knew data centers would also be a great hedge for our long healthcare exposure (why’d you have to get bullish healthcare, Jim!?). He even said the quiet part out loud, “these things are very unpopular.”
To recap on sentiment and positioning:
- Most data center/bitcoin miner plays are down 40-50% from their highs.
- The news cycle is filled with data center moratoriums and politicians battling against building more in their jurisdictions.
- Jim Cramer is selling his data center stocks.
We’ve established that data centers are properly hated (for now). Next let’s examine the tape.
Technicals: My “New Favorite” Chart Setup
As I mentioned earlier, a big part of my evolution as an investor is focusing less on breakout/momentum trading and more on buying deep pullbacks and stocks at long-term support.
I’ve written about it before, but it’s worth mentioning here for two reasons:
- I wouldn’t have spotted the data center trade at this point a year ago, because I would’ve hated the chart.
- An investor’s job is to constantly evolve and improve to become like a cockroach … invincible to the market’s ever-changing dynamics.
That’s the beauty of having Mike and Dean on the team. They handle the breakout and momentum trading for Alex and me, so now I can 100% focus on bombed-out inflecting stocks in deep pullbacks or bouncing off long-term support.
Luckily I have mentors like Judd Arnold to copy technique and learn the “muscle memory” of buying bombed-out charts on inflecting stocks. Which brings us to data centers.
Data center stocks aren’t “bombed out” in the traditional sense. They’re down 40-50% from their highs. But importantly, they sit at or near long-term moving averages and/or lower bollinger bands. This allows us to get large notional size for small actual risk.
Here’s a list of data center/bitcoin miners and their relation to the lower bollinger band on the weekly chart:
- CIFR: 13%
- WULF: 12% ➢ HUT: 17%
- MARA: 13%
I want to remind you that these are all basically one trade/factor. If one works, they all will work.
My favorite play here is Hut 8 (HUT), which I’ll explain in the next section. But one reason it’s my favorite is because it has the best technical setup in the space (see below).
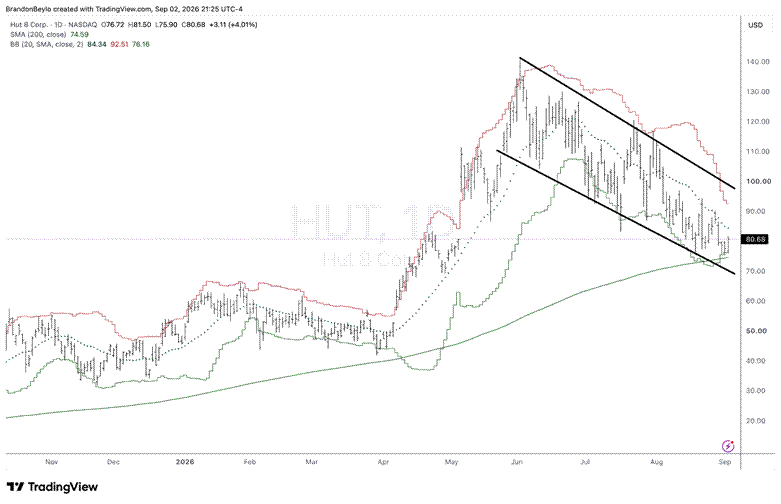
Notice how the stock is teeing off its 200D MA down 43% from its highs. This allows us to risk little actual capital for a high notional position … our ideal setup.
Fundamentals: Scarce Assets, Solid Economics, Cheap Price
Morgan Stanley has written extensively about the Power Shell Provider (PSP)/data center/bitcoin miner trade. The central valuation theme is that at today’s prices you’re getting a discount on contracted MW and getting the rest of the pipeline + other assets for free.
But before we get to the individual equity value, the data center thesis rests on five main conditions:
1. AI Capabilities will increase at non-linear rates.
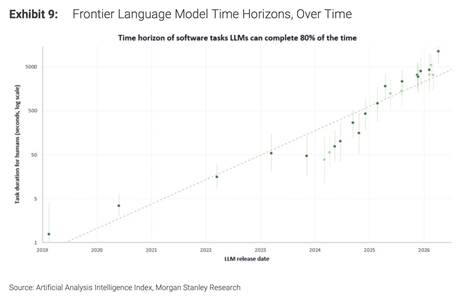
2. Compute demand will outpace supply.
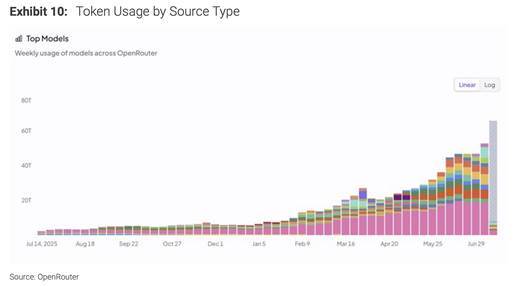
3. Power will remain one of the most important bottlenecks in the AI race.
See Elon’s recent tweet highlighting the importance of finding enough power (emphasis mine):
“Consensus estimate is that ~15GW of AI compute produced in 2027 cannot be turned on in 2027.
This is harder than just finding power, as you also need to build out all the transformers, wiring, liquid-cooling, (massive) chillers & complex networking.”
There’s also a scenario where even if we secured all data center power access, we’d still fall short of the required power access.
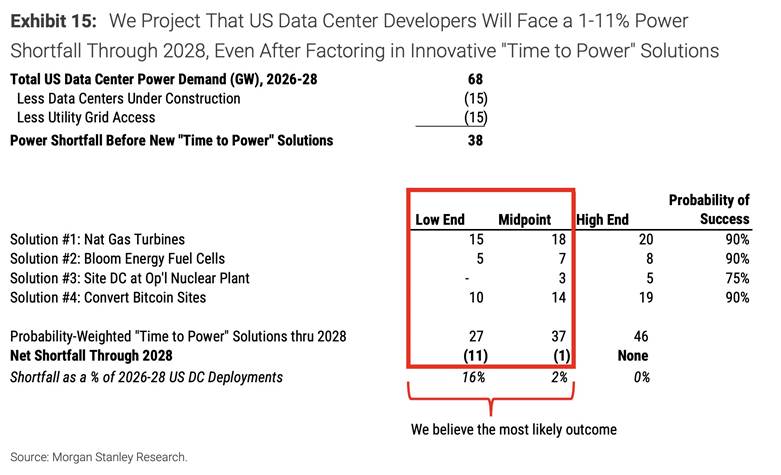
4. Data centers will be the most reliable form of “quick power” for frontier labs.
The beauty of these bitcoin miners is that they already have power access. There’s no need to wait years for government and regulatory approval. I like how Morgan Stanley puts it, “the data center developer is reusing existing grid access rather than requesting new, incremental grid access.”
Of course this is also a Resource Nationalism play. We’re racing against China for AI Supremacy. Every second counts. Why not work with companies that are (pun intended) plug and play?
5. Data centers will become scarce assets with long-term earnings power.
All these moratorium requests are examples of NIMBYism. It’s like how everyone loves what copper provides them (smartphones, electricity, digital connectivity), but nobody wants a copper mine in their backyard.
Back to the Morgan Stanley report (emphasis mine):
“Data center development is quickly becoming a NIMBY (Not in My Backyard) issue with communities increasingly pushing back and getting projects cancelled. This came to a head last week, when New York State issued a one-year pause on all data center construction projects. Companies must find ways to address local concerns about environmental and water-related externalities, while also ensuring that consumers are insulated from potentially higher electricity bills.”
Again, bitcoin miners already have the power access and brownfield site access. That brings us to Hut 8 (HUT).
Hut 8 (HUT): Large Contracted MW, Strong Balance Sheet, Bitcoin Kicker
There are many ways to play the bitcoin miner/data center trade. So why HUT versus the others? A few reasons:
- They have the cleanest balance sheet
- Have issued investment grade debt for their projects
- Hyperscaler customers allow them to issue IG debt
- Construction backed by Jacobs Engineering
- They have $1.5B in bitcoin on their balance sheet ($12/share)
- Trading below its contracted MW value
Since all of these ideas are roughly the same, my preference came down to: balance sheet risk, customer quality, and downside protection. Balance sheet risk and customer quality go together.
Higher quality customers mean lower cost debt. HUT has three hyperscaler, Tier-1 customers for its three contracted projects, which allowed it to raise debt at ~7% yield-to-worst.
Check out the contract breakdown below highlighting the debt terms, and most importantly, the equity value created per watt.
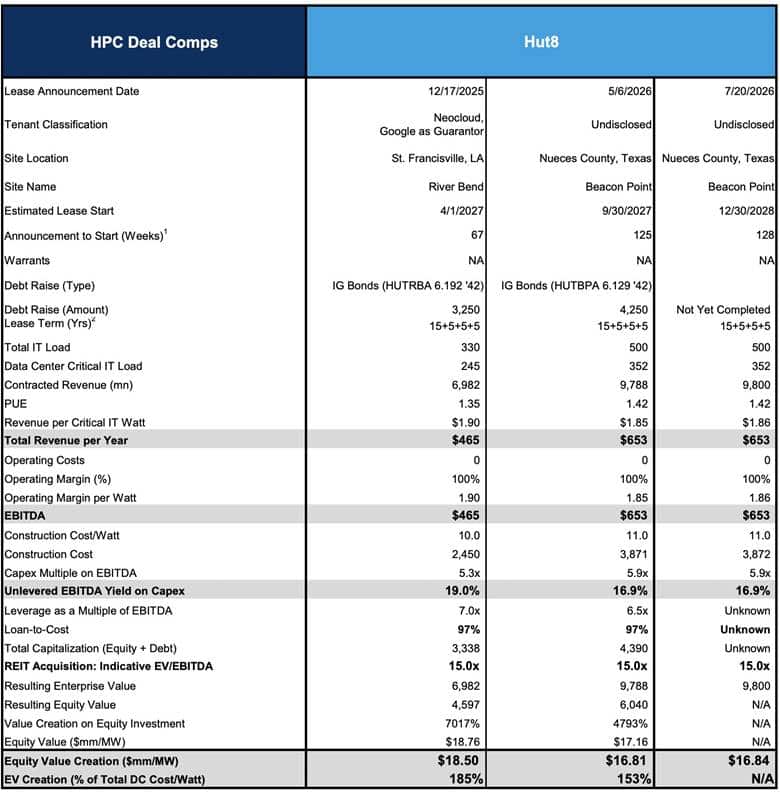
HUT has generated ~$17/W in equity value from its three contracted projects. The stock currently trades at ~$10/W for the entire company.
Also, HUT arranged the debt financing at the project level, so the parent company holds no long-term debt on its balance sheet.
The company also owns 20,000 BTC and has 6,000 MW of uncontracted critical IT MW. This is where things get exciting.
Let’s do the napkin math.
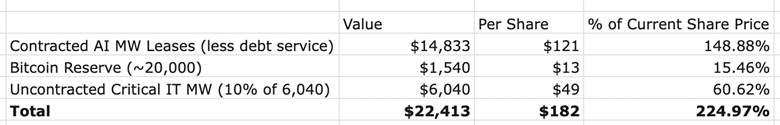
The big idea is that you’re paying 33% less than the value of the contracted MW leases today and getting 20,000 BTC and 6,040 MW of uncontracted IT MW for free.
I also added an extra layer of conservatism in my uncontracted MW value: 10% converted at $10/MW (versus $17+ today).
Remember, the contracted AI leases are triple-net leases with Tier-1 tenants where HUT raised project financing at 7%. That’s worth ~$121/share versus today’s price of $81/share.
Conclusion: A Trifecta Lens Trade in Data Centers
Bitcoin miners/data center stocks are a Trifecta Lens Setup:
- Sentiment/Positioning: Hated by politicians and Jim Cramer with most stock prices down 40-50% from June highs, yet long-term secular drivers remain intact.
- Technicals: Stocks are hugging lower bollinger band and key moving averages allowing for tight risk control and large notional size.
- Fundamentals: You can buy the stocks for less than their contracted MW value and get 100% of future MW backlog and extra assets (like BTC) for free during one of the greatest bull markets for energy and power in recent memory.
I hope you guys enjoyed this report.
Until next week!